
BEIJING
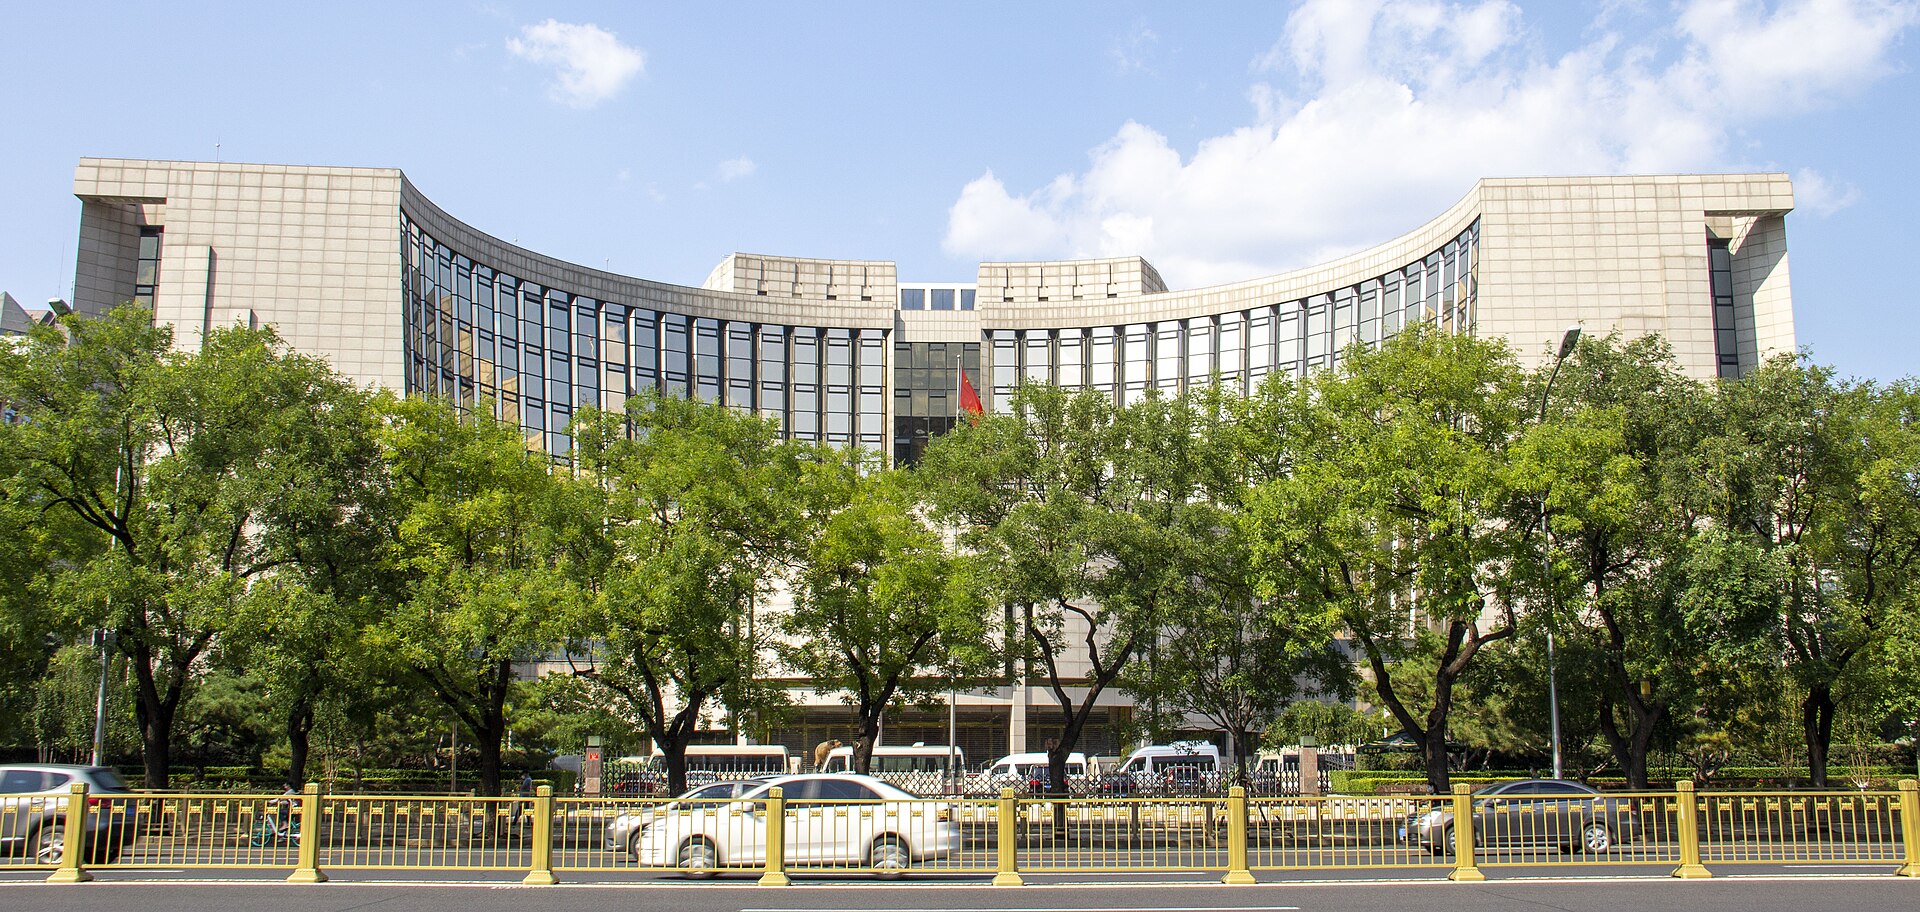
China's central bank did nothing on Tuesday, and the nothing was the news markets had priced in for a week. The People's Bank of China (PBOC) kept its benchmark lending rates unchanged for the 17th straight month in October, holding the one-year loan prime rate at 3.00% and the five-year rate at 3.50%, in line with market expectations, Reuters reported. In a Reuters survey of 22 market participants conducted on Monday, every single respondent predicted no change to either rate — a unanimity that tells its own story about how completely the decision was telegraphed.
Why a hold, and why now
The steady LPRs suggest policymakers are in no rush to roll out fresh monetary easing after a strong third-quarter GDP outcome, as they focus on reforming the loan pricing framework and improving monetary policy transmission. China's economy expanded 4.5% year-on-year in the third quarter, topping forecasts — a rebound off three-year lows, driven by roaring exports that offset consumers' tight grip on their wallets. Previously reported the GDP figure and the two-speed economy behind it in its coverage of the third-quarter numbers. Market participants expect Beijing to reach its 2026 growth target of 4.5% to 5.0% without resorting to additional stimulus, helped by a strong start to the year and some recent modest fiscal and monetary support.
How the rate is set explains why it so rarely surprises. The loan prime rate, normally charged to banks' most creditworthy clients, is calculated each month after 20 designated commercial banks submit proposed rates to the PBOC. When the economy is growing at target and the central bank's attention is elsewhere — on the plumbing of the system rather than its price — the submissions cluster exactly where the previous month's fixing landed, and the streak extends by another month. Seventeen months of that is not drift; it is a policy stance, maintained while some major economies tilt toward tighter monetary policy to contain inflation pressures and China's long-dated bond yields hover near a 15-month low.
The reform underneath the hold
The more consequential news came a day earlier, from the governor himself. The PBOC is considering switching its main policy rate to the overnight reverse repurchase rate, in a shift aimed at improving the transmission of monetary policy to support the economy. The bank will also issue policy guidance to advance reform of the loan pricing benchmark, shifting lending away from a relatively narrow reliance on the LPR toward a more diversified set of benchmarks, Governor Pan Gongsheng said on Monday.
In practical terms, some financially strong companies could opt for either the overnight reverse repo rate or the LPR as the benchmark for floating-rate loans, while the overnight rate could also serve as an alternative pricing benchmark for bonds and financial derivatives, Pan said. Analysts at Huatai Securities described the design as tiered — giving large firms the option while keeping small and micro enterprises and individuals anchored to the LPR — primarily aimed at avoiding a one-off shock to the existing pricing system. "As more corporate loans are linked to the overnight repo rate, the rate's fluctuation range is likely to narrow, enhancing the stability of liquidity conditions," Huatai said. In other words, the LPR may matter a little less with each passing month — which is one more reason a 17th consecutive hold can pass almost unnoticed.
The soft spots that have not healed
None of this means the economy underneath the headline rate is uniformly healthy. China's new home prices fell again in September, extending a slump of more than three years and suggesting policy support has yet to spark a broad-based recovery in housing demand. Analysts warn that the growing reliance on external drivers — exports carrying the growth number while domestic consumers hold back — is deepening structural imbalances in the world's second-largest economy. It is a two-speed economy: fast enough at the top line to make stimulus unnecessary, slow enough in the property market and the shopping street to make it tempting.
For markets outside China, Tuesday's decision landed quietly. Currency coverage noted the New Zealand dollar holding steady in early Asian trading after the PBOC left the LPRs unchanged, with traders' attention already turning to data later in the week and to the Federal Reserve's October 27–28 meeting, where officials are expected to leave U.S. rates unchanged as well. Sometimes the most important central-bank decision of the morning is the one that changes nothing — and signals, in the small print of a governor's speech, that the machinery itself is what is about to change.
What the hold means for borrowers — and what comes next
The two rates do different work in Chinese households and boardrooms. The one-year LPR is the reference for most corporate and household lending, while the five-year rate is the benchmark against which mortgages are priced — which is why a 17-month hold on the five-year rate lands directly on a property sector that has been shrinking for more than three years. Every month the five-year rate stays at 3.50%, the cost of a new mortgage in China stays exactly where it was, for better and for worse: no new burden on buyers, but also no new relief for a housing market whose prices fell again in September. That trade-off is precisely the one Pan's pricing reform is designed to loosen, by letting different borrowers price off different benchmarks instead of forcing the entire economy through a single monthly fixing.
The next tests arrive quickly. Investors spent Monday watching a key financial forum in Beijing, where Pan was due to speak, for clues on the country's monetary path — and the governor's reform comments, rather than the rate decision itself, were what they took away. The November LPR fixing will be read the same way: not for whether the numbers move, but for whether the share of lending priced off the overnight repo rate has begun to grow. Until the reform changes the plumbing, the streak itself is the signal — a central bank confident enough in 4.5% growth to leave its headline prices untouched, and busy enough redesigning the system underneath them that the prices matter less each month.
Sources · 4 sources
- Reuters — China leaves loan rates steady for 17th consecutive month
- Reuters via The Hindu BusinessLine — China keeps benchmark lending rates unchanged for 17th straight month
- Reuters — China set to leave benchmark lending rates unchanged for 17th month
- Reuters via 93.5 The Lloyd — China set to leave benchmark lending rates unchanged for 17th month