
GE Aerospace gave Wall Street almost everything it could have asked for on Tuesday morning, October 20, 2026 — a double-digit earnings beat, a 49% surge in orders, a raised outlook for the year — and the market’s answer was to sell the stock anyway. According to Stocktwits, GE Aerospace reported third-quarter adjusted earnings of $2.25 per share, well ahead of the $2.01 consensus estimate, on adjusted revenue of about $13.3 billion against expectations of roughly $12.88 billion. The Motley Fool reported that the shares slipped 4.40% to $297.59 by late morning, the fourth consecutive quarter in which GE stock has fallen on an earnings beat, according to Stocktwits. That tension — a business executing at full throttle and a share price that refuses to applaud — is the whole story of this print.
The numbers were not subtle
Start with demand. Total orders reached $19.0 billion in the quarter, up 49% from a year earlier, which works out to a book-to-bill ratio of 1.35 — for every dollar of revenue GE Aerospace shipped, it booked $1.35 of new work, according to The Motley Fool. TradingView News reported that GAAP revenue rose 16% to $14.12 billion, while adjusted revenue increased 18% to $13.29 billion, and GAAP profit came in at $2.81 billion. Operating profit surged 30% to about $3.0 billion, and the adjusted operating margin expanded 220 basis points to 22.5%, according to TradingView News. Adjusted earnings per share rose 36% from a year earlier, Seeking Alpha reported, beating the consensus by $0.24.
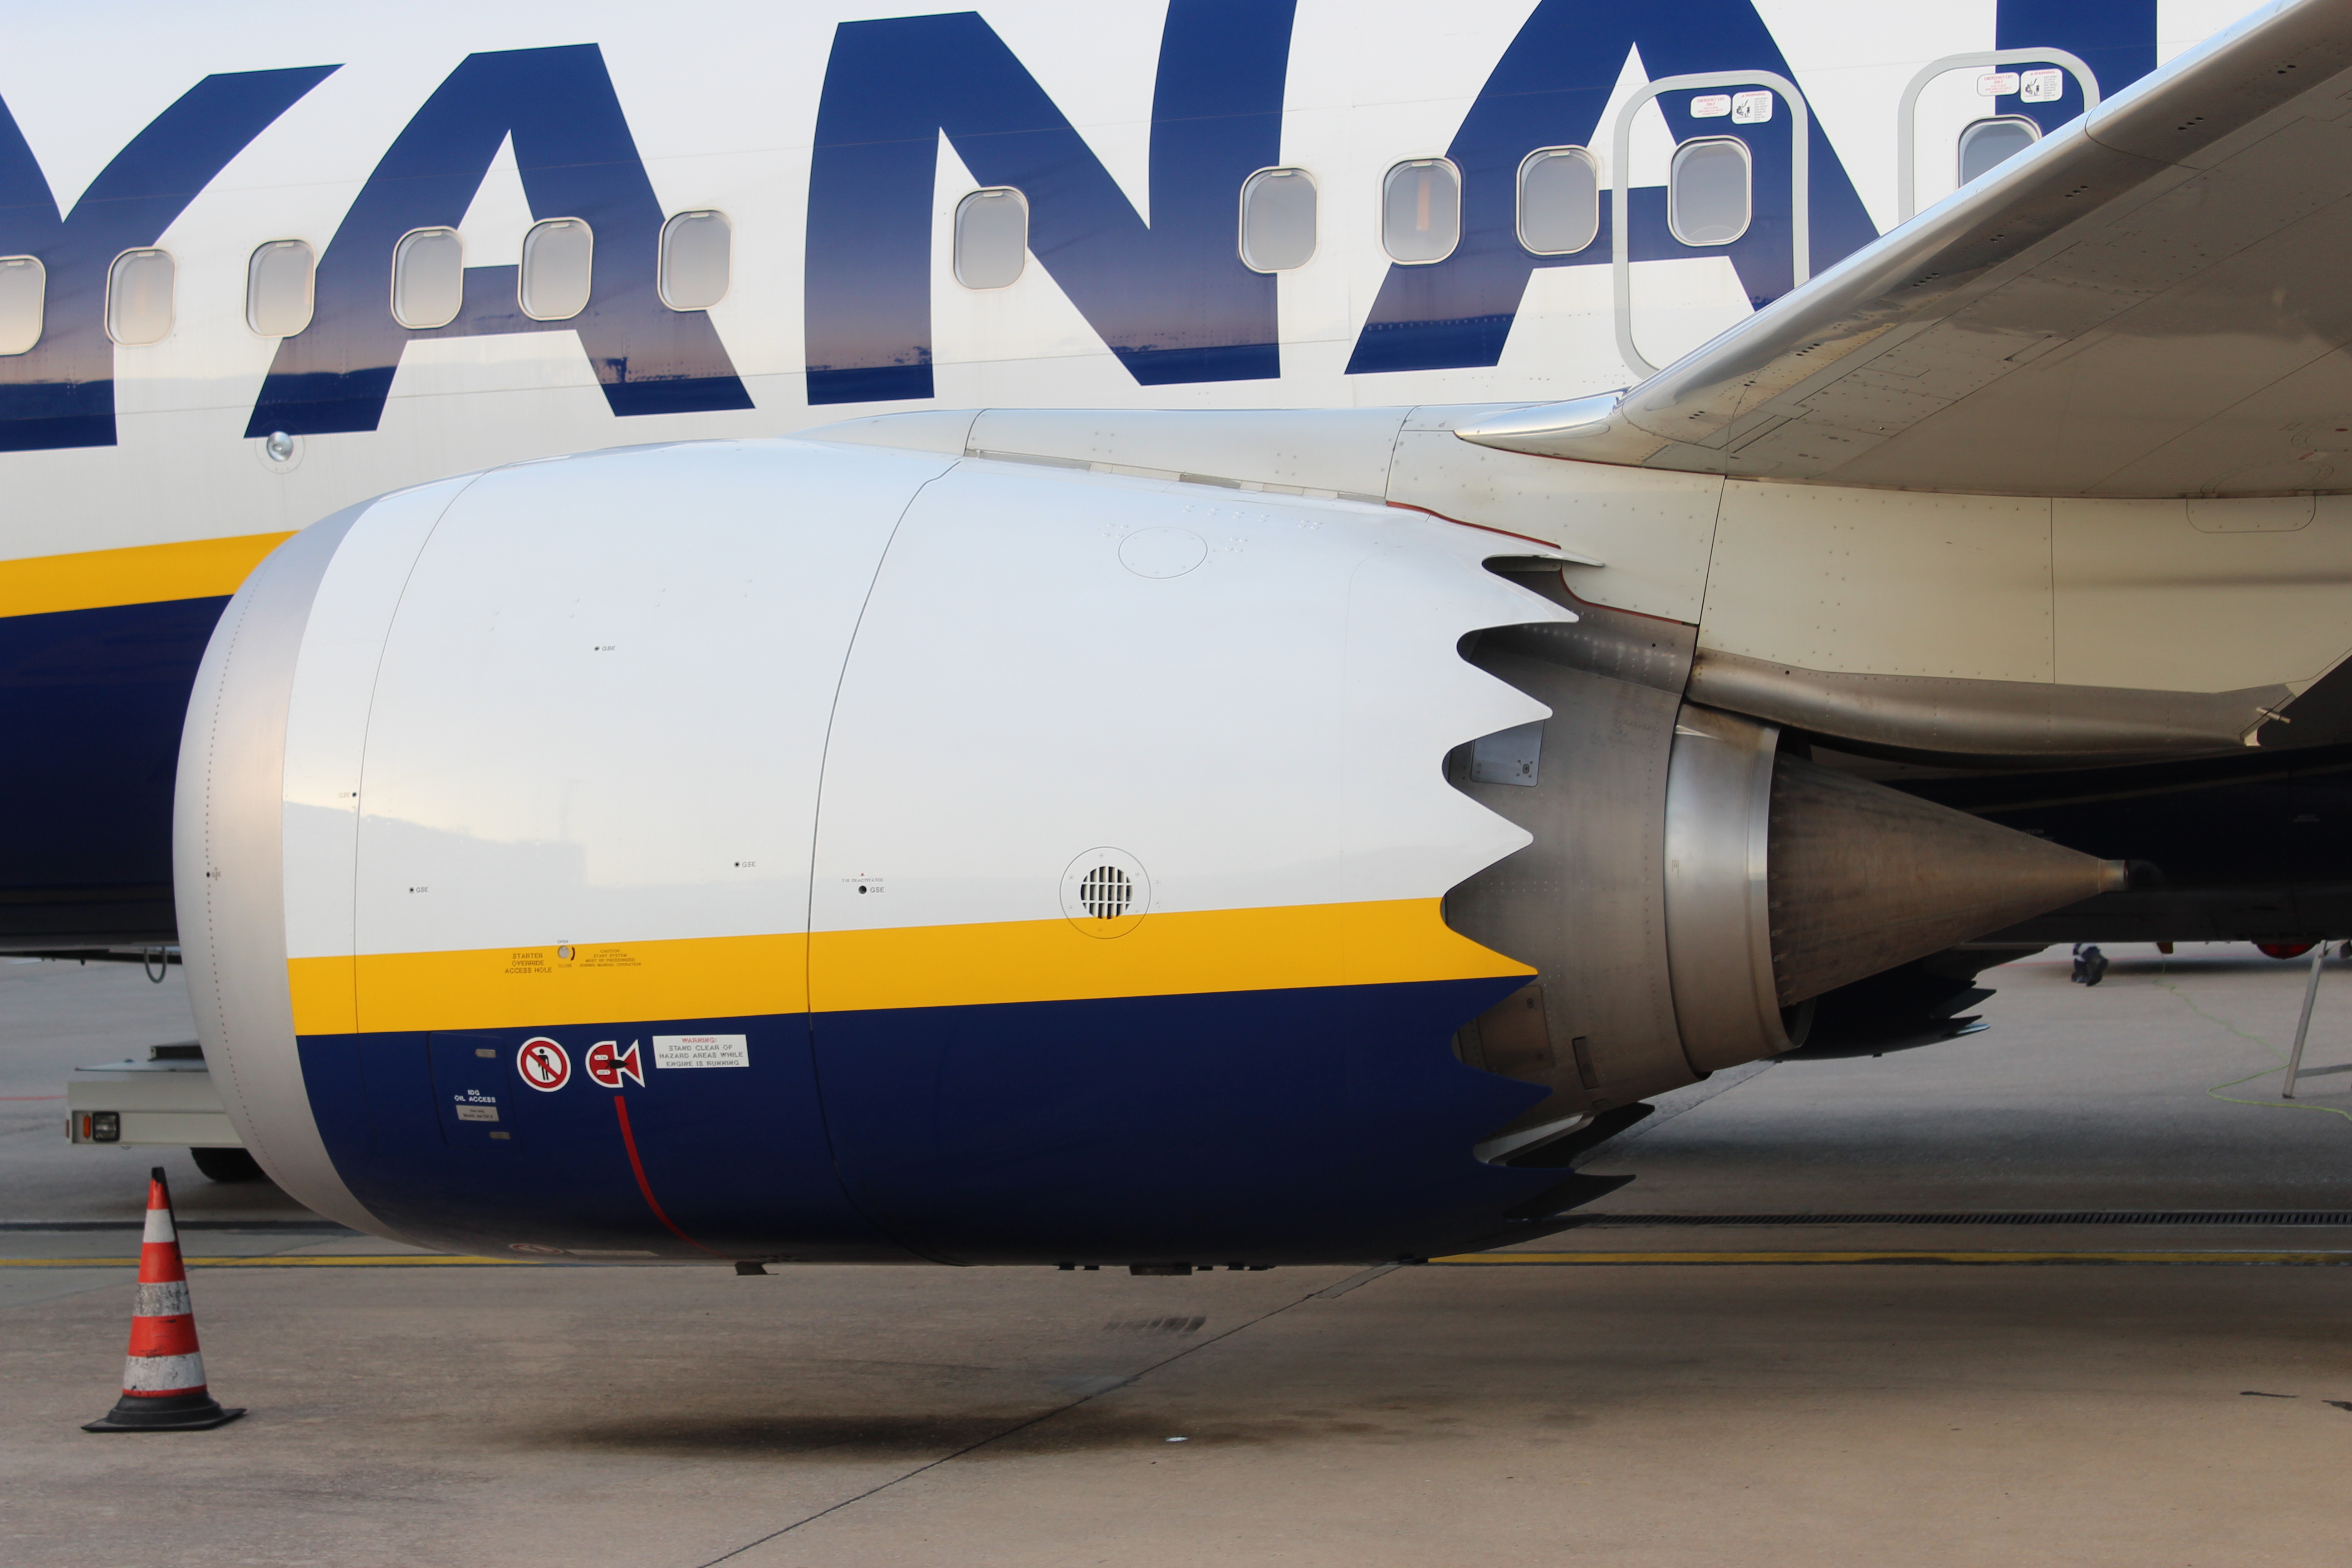
The engine of the quarter, as usual, was Commercial Engines & Services. Revenue there grew 21% to $10.34 billion, driven by services growth of 17% and equipment growth of 38%, according to TradingView News. Commercial services orders rose 23%, spare-parts revenue increased more than 20%, and internal shop-visit volume for the LEAP engine family rose more than 40% year over year. Defense & Propulsion Technologies grew more slowly — revenue up about 6.7% — a gap The Motley Fool noted in contrasting the 21% commercial growth with roughly 7% on the defense side. GE also announced an agreement to acquire Consolidated Precision Products, a maker of mission-critical castings, to expand capacity for new engine technology, according to TradingView News.
A raise, not just a beat
Management did not stop at a good quarter. GE Aerospace raised its full-year 2026 guidance across the board: adjusted earnings per share are now expected at $8.00 to $8.10, up from $7.65 to $7.85 previously, according to Stocktwits. Adjusted revenue growth is now seen at 19% to 20%, operating profit guidance rose to $10.9 billion to $11.0 billion from $10.55 billion to $10.75 billion, and free cash flow guidance increased to $9.1 billion to $9.4 billion from $8.9 billion to $9.2 billion. “We delivered strong results this quarter as solid demand drove orders up 49%,” CEO H. Lawrence Culp Jr. said, according to Stocktwits, adding that the company continues to “build momentum.” The company also pointed investors toward 2027, saying it expects commercial services revenue to grow at a low-double-digit rate next year, backed by a commercial services backlog above $170 billion, according to Stocktwits.
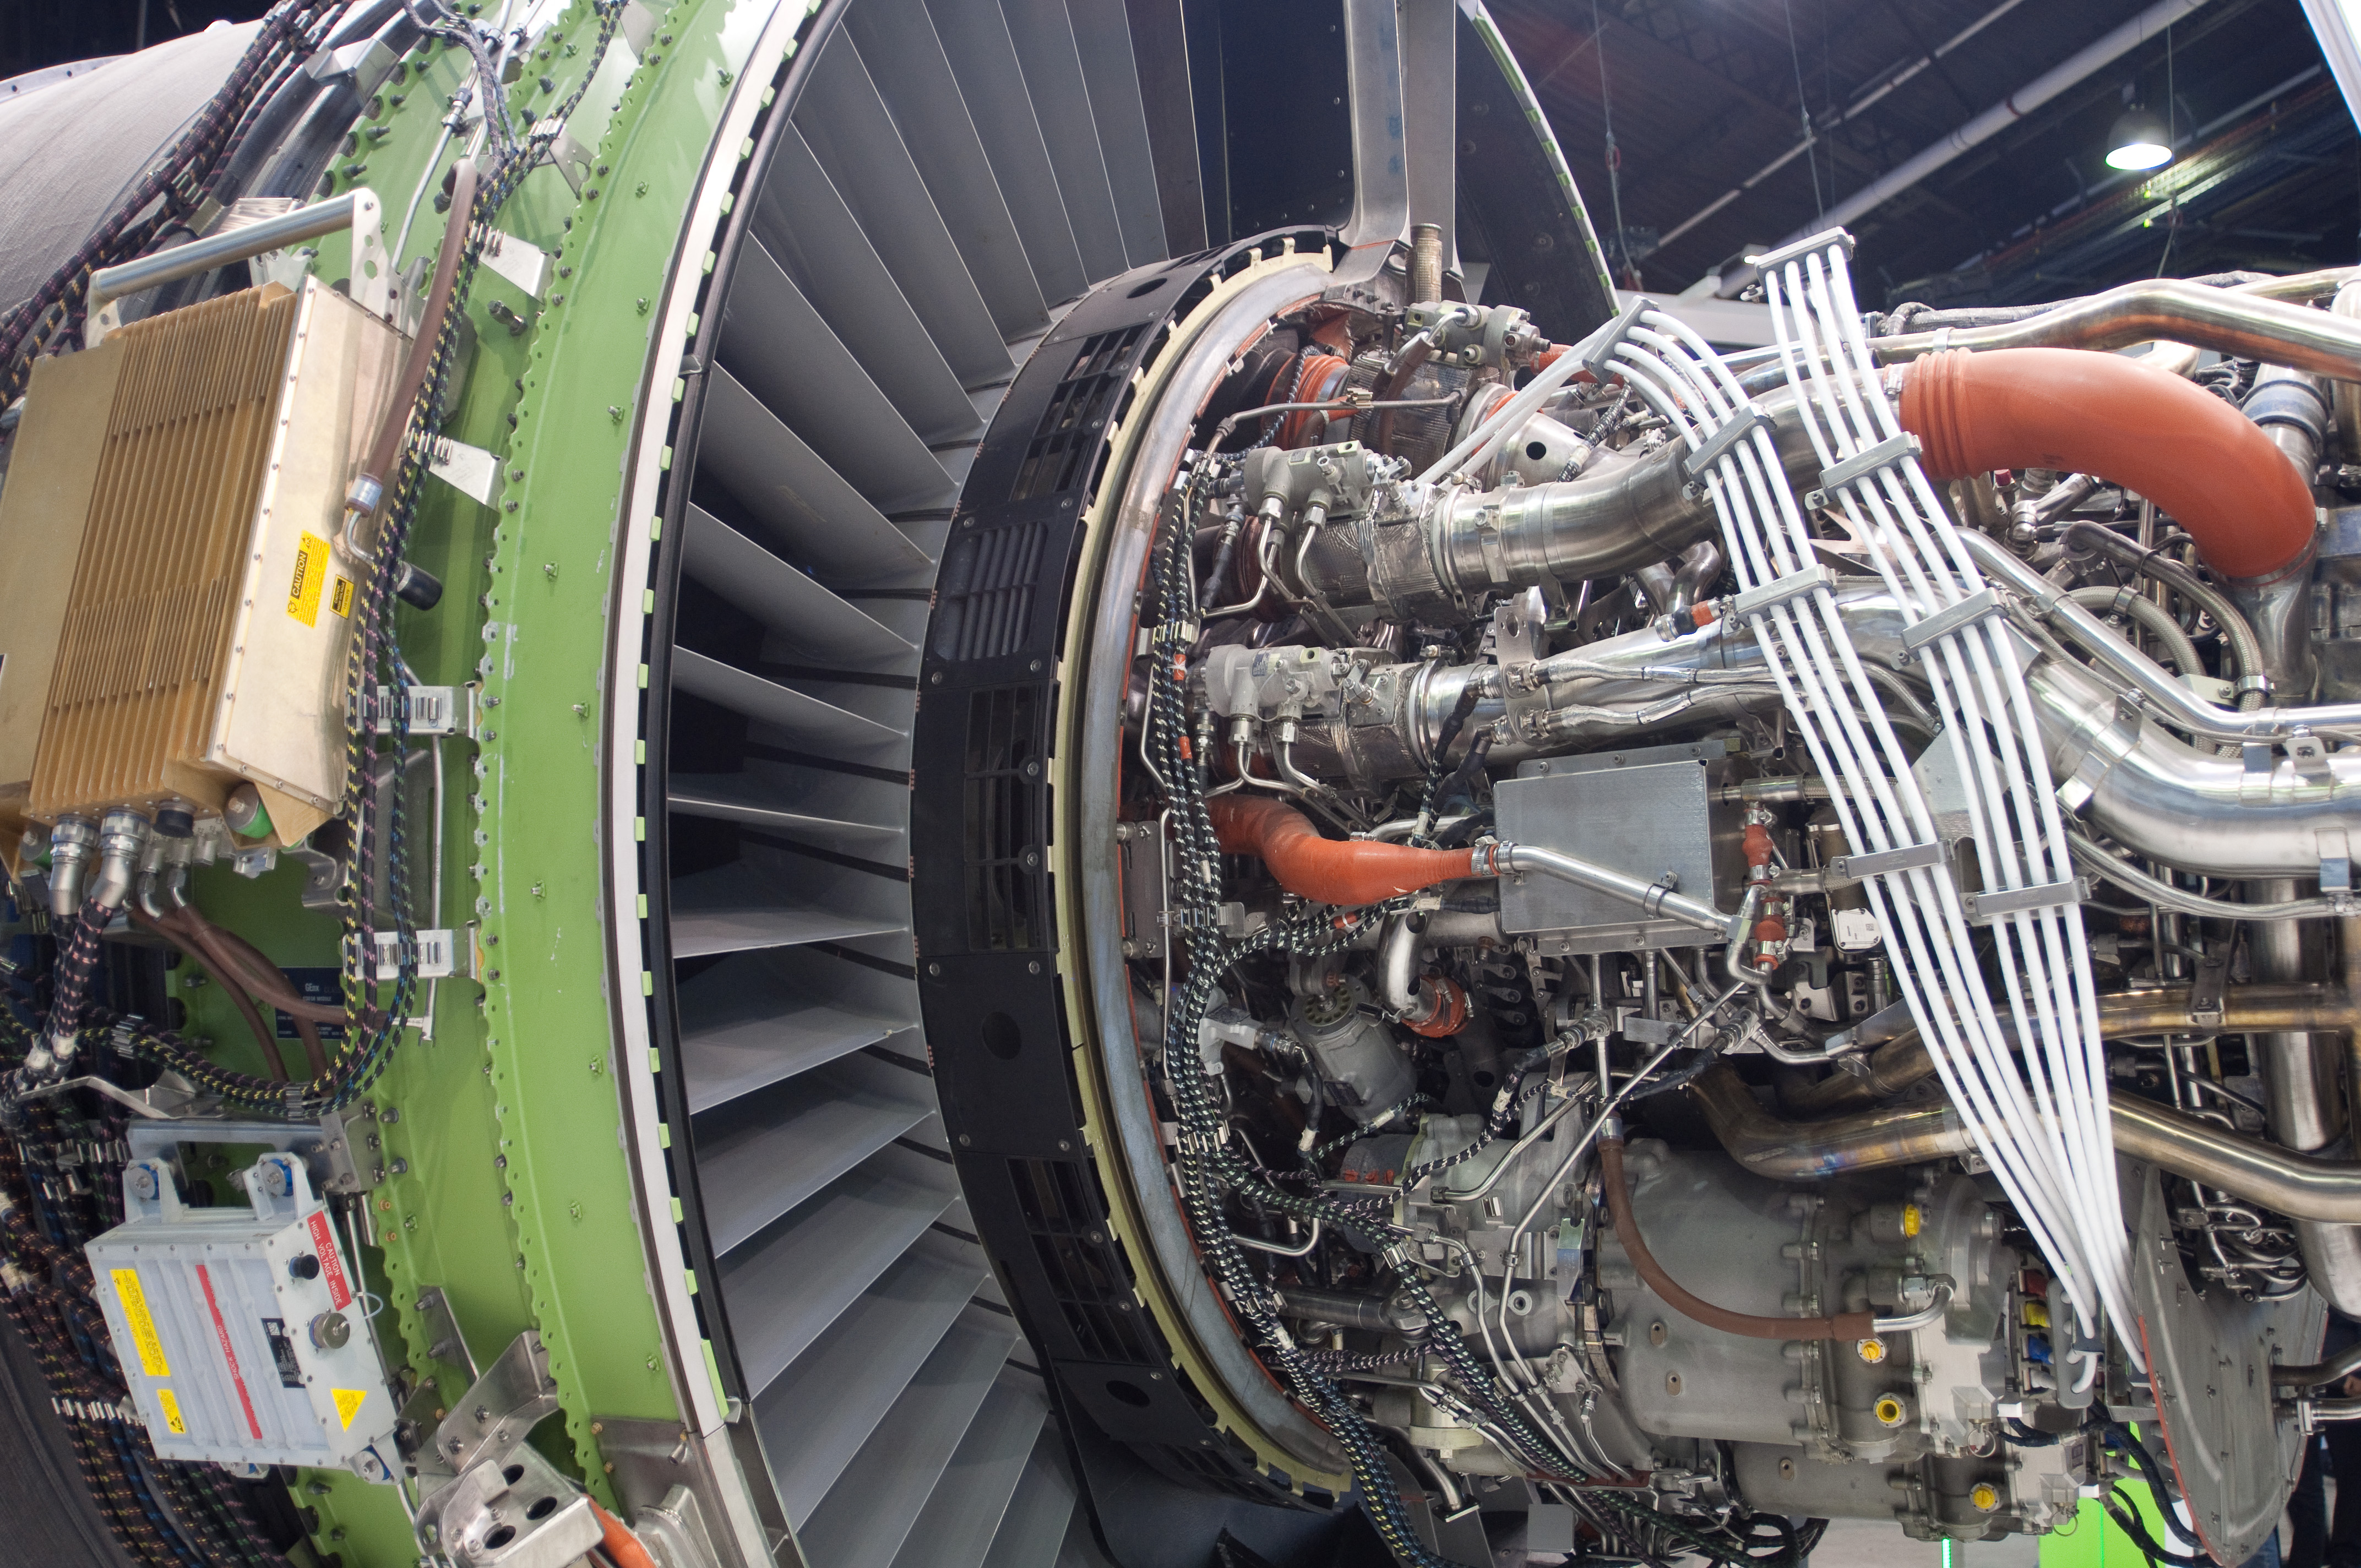
That backlog figure deserves a pause. A services backlog above $170 billion is, in effect, a multi-decade annuity: every LEAP and GEnx engine GE delivers today returns to its shops for overhauls, spare parts and repairs for the next twenty-plus years, at the fattest margins in the business. It is why the aftermarket, not new-engine sales, is the profit core of modern aerospace — and why the market watches the services growth rate the way it watches a hawk.
So why did the stock fall?
The honest answer is valuation, with a side of cash. The Motley Fool noted that free cash flow declined year over year to about $2 billion in the quarter and missed analyst targets, even as the full-year outlook was raised. Put the raised guidance together and GE Aerospace still trades north of 36 times free cash flow with an 18% growth rate — “at the upper edge of what I’d consider a ‘fair price’ for GE stock,” The Motley Fool wrote, “and probably another reason the stock is falling after an earnings beat.” When a stock is priced for perfection, a beat is merely the admission ticket; investors start hunting for the flaw in the mix instead.
There were a few places to hunt. Briefing.com reported that equipment grew faster than services in the quarter, which pressed the Commercial Engines & Services margin down 10 basis points year over year to 27.9%, and that deferred financial recognition on the GE9X program and cost pressures blemished an otherwise robust performance. New engines are sold at thin — sometimes negative — margins; the money arrives later, in the aftermarket. A quarter tilted toward equipment deliveries therefore looks better on revenue than it feels on profit quality, and traders who have watched this movie four quarters in a row know exactly where to poke.
None of that changes the direction of the business. Orders up 49%, a 1.35 book-to-bill, services backlog above $170 billion and a guidance raise on every line is not a company losing altitude. It is a company whose stock had already climbed to cruising altitude before the results landed. Tuesday’s selloff says less about GE Aerospace’s quarter than about what investors had already paid for it — and about a market that, this earnings season, is grading the industrial giants on a curve strict enough to humble even a $19 billion order book.
Sources · 4 sources
- Stocktwits — GE Stock Tumbles Despite Earnings Beat As Cost Pressures Margins, Cash Flow (October 20, 2026)
- The Motley Fool — Why GE Aerospace Stock Dropped After Beating Earnings (October 20, 2026)
- TradingView News — GE Aerospace posts Q3 2026: Revenue $14.12B, Profit $2.81B, Adj. EPS $2.25 (October 20, 2026)
- Seeking Alpha — GE Aerospace Non-GAAP EPS of $2.25 beats by $0.24 (October 20, 2026)