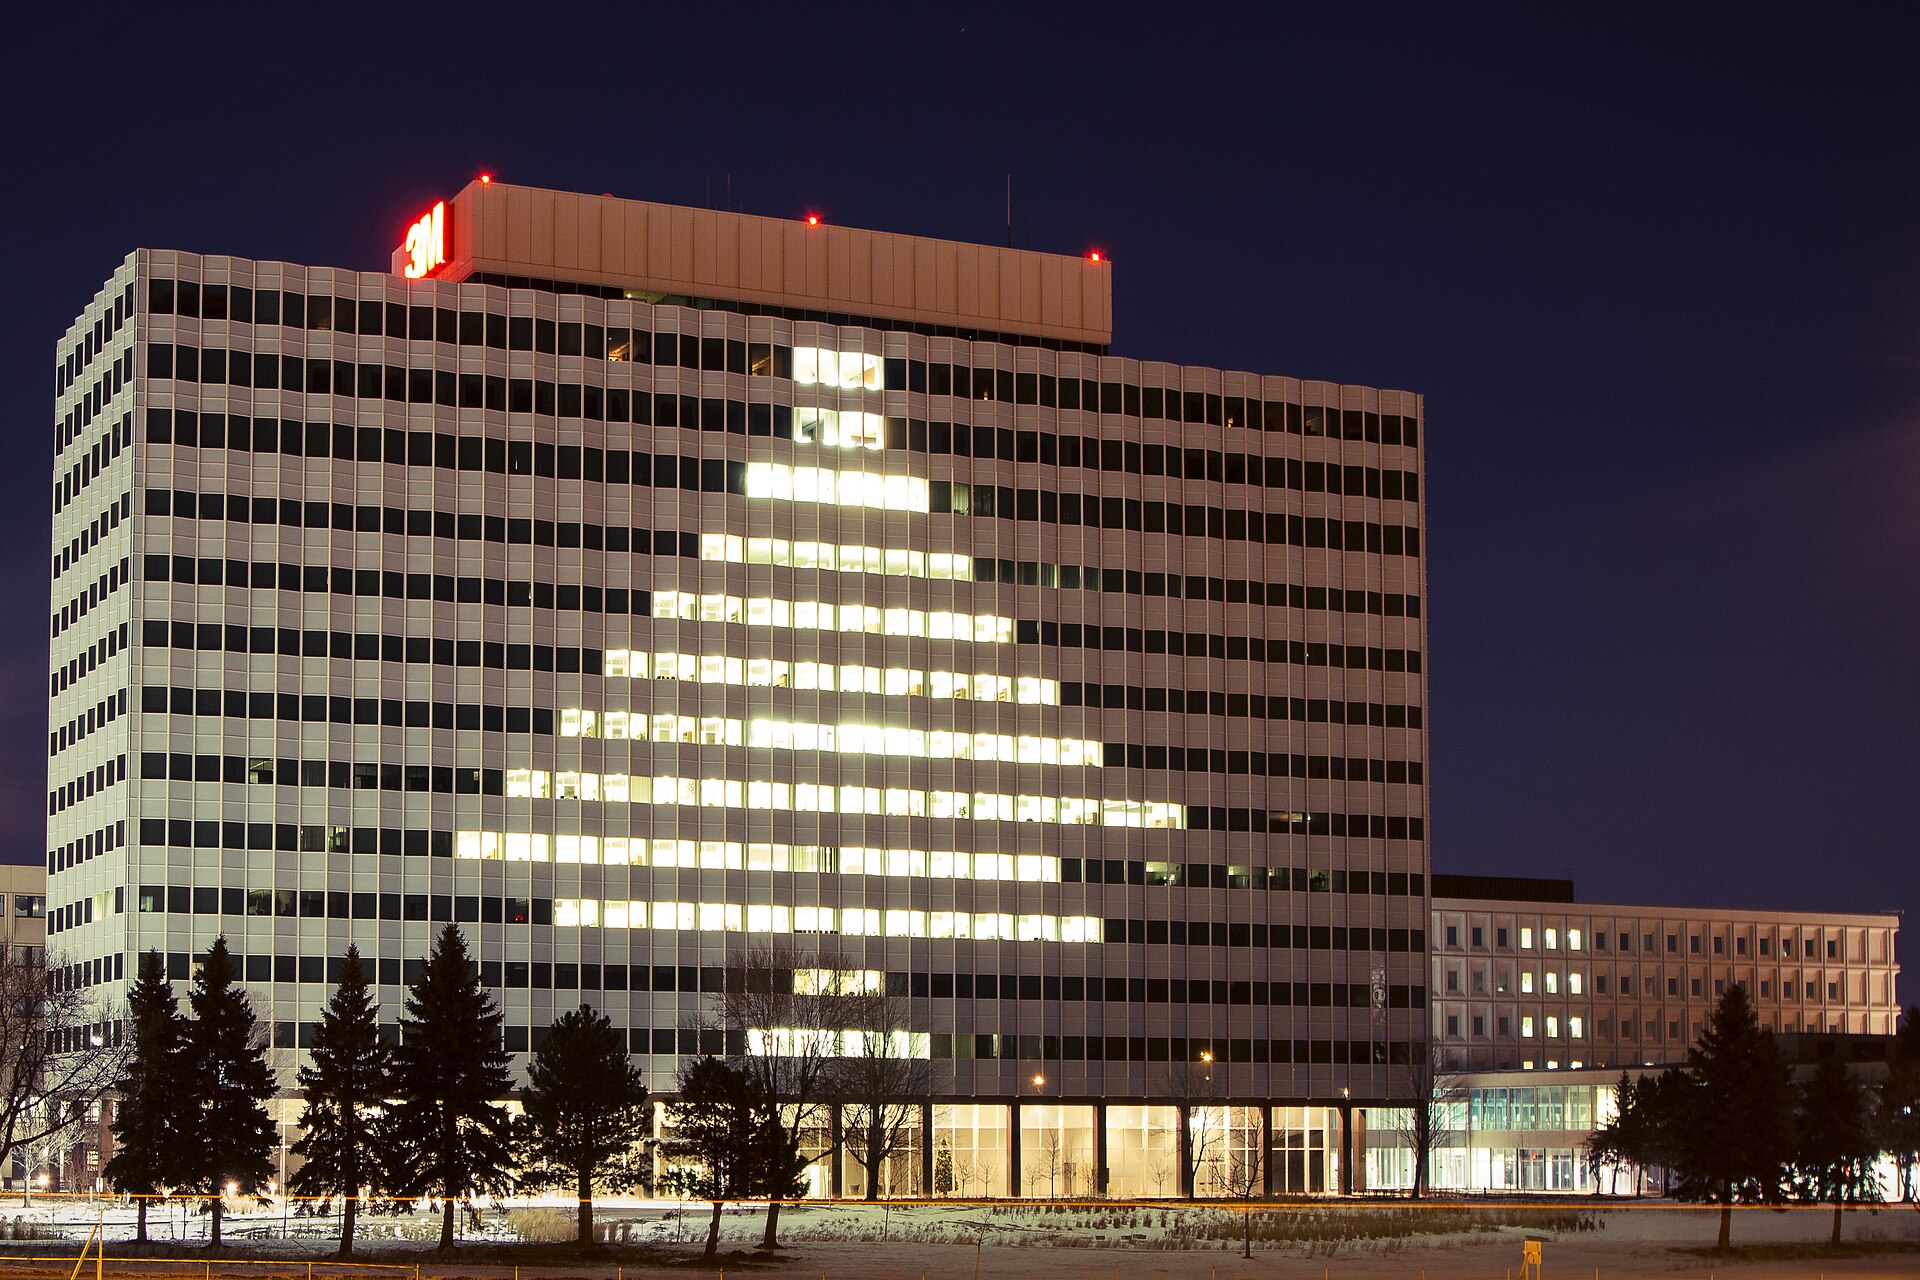

3M is not supposed to be an AI stock. It makes Post-it Notes, respirators and industrial adhesives. But on Tuesday, October 20, 2026, the Minnesota conglomerate reported a third quarter that beat on profit, raised its full-year guidance again — and attached itself directly to the data-center buildout through an expanded deal with Amazon. Investors responded the way they respond to anything with “optical connectivity” in it this year: the stock jumped about 5.2% in the afternoon session and closed at $171.50, up 5.9%, according to TradingView News’ StockStory report.
The quarter: a clean profit beat, a hairline revenue miss
3M reported adjusted earnings of $2.50 a share, up 12% year over year, beating the consensus of roughly $2.38 to $2.40, according to Zacks and Seeking Alpha. GAAP earnings were $2.63 a share. Sales were $6.58 billion by Zacks’ tally — about $6.6 billion as the company rounded it — up 4.2% year over year on an adjusted basis, a shade below the $6.61 billion Zacks consensus; Seeking Alpha put the revenue miss at about $10 million. Adjusted organic sales grew 3.3%. Profitability was the strongest part of the print: the adjusted operating margin reached 26.2%, up 110 basis points, while the GAAP operating margin was 23.7%, up 150 basis points, according to the company’s results as reported by Zacks and TradingView.
The segments told a familiar two-speed story. Safety & Industrial was the engine, with sales of $3.18 billion, up 9.1% year over year and ahead of the $3.12 billion estimate, according to Zacks. Consumer was essentially flat, with sales of $1.31 billion, down 0.4%. Transportation & Electronics operating income came in at $468 million against a $497.42 million estimate, per Zacks — the soft spot in an otherwise strong quarter, and the part of the business most exposed to consumer electronics and auto demand. Adjusted free cash flow was $1.2 billion, and 3M returned $600 million to shareholders in the quarter, according to the company’s release as summarized by Tickeron and TradingKey.
The guidance raise — again
The number that mattered most may have been the one about the future. 3M raised its full-year 2026 adjusted earnings guidance to $9.10 to $9.15 a share, above the roughly $8.93 consensus, according to Tickeron’s earnings recap. TheStockObserver described it as the third consecutive quarterly guidance raise — a streak that, if it holds, marks a genuine change in posture for a company that spent years guiding cautiously and cleaning up legal and portfolio problems. TradingKey’s earnings-call summary added supporting detail: orders grew at a high-single-digit rate and backlog rose by the high teens, with management expecting organic growth of just over 4% in the fourth quarter.
This is the Bill Brown turnaround in its current form. Since taking over, Brown has pushed restructuring, productivity and portfolio simplification — including 3M’s exit from PFAS manufacturing — and the margin line is where the work shows up first. A 26.2% adjusted operating margin, up 110 basis points in a quarter when one major segment missed its profit estimate, is the kind of evidence that persuades investors the restructuring is structural rather than cosmetic.
The Amazon twist
Then there was the deal that turned a solid industrial print into a 5.9% stock move. 3M announced an expanded commercial relationship with a subsidiary of Amazon to scale optical-connectivity and other data-center products — the hardware that moves data between server racks at the speed AI clusters demand. As part of the arrangement, Amazon received a warrant for up to 3.2 million 3M shares, valued in coverage of the deal at about $521.4 million, tied to $6 billion in cumulative sales over seven years, according to the company’s announcement as reported by StockStory via TradingView and Tickeron. In plain terms: if Amazon buys enough of 3M’s data-center gear over the next seven years, it earns the right to own a meaningful slice of 3M itself.
3M paired the Amazon news with a collaboration and planned minority investment in Taiwan-based Genius Electronic Optical, aimed at expanded-beam optical manufacturing — the same technology family at the heart of the Amazon relationship. TradingView’s report on the results noted management expects expanded-beam optics revenue of roughly $40 million in 2026, growing to approximately $80 million to $100 million in 2027. Those are small numbers next to $6.6 billion in quarterly sales. But they are growing numbers in the one market investors currently pay a premium for, and they give a 124-year-old industrial company a credible seat in the AI infrastructure trade.
What the market did with it
Traders did not wait for the fine print. StockStory, via TradingView, reported the shares jumped 5.2% in the afternoon session before closing at $171.50, up 5.9% — a large move for a stock that, as StockStory noted, has had only four moves greater than 5% over the past year. Options traders leaned in as well, with unusual call buying of 24,152 calls, up 159% versus typical volume, according to market coverage of the session. The comparison traders kept making was with 3M’s second quarter, when the stock gained more than 8% after another beat-and-raise — a pattern that is starting to look like a habit.
The honest caveats
A fair reading of the quarter keeps two cautions in view. Revenue missed consensus, if only by about $10 million, and Transportation & Electronics — a segment that should benefit from the same electronics cycle powering the data-center story — came in light on profit. Consumer was flat to down. The beat, in other words, was manufactured the way turnarounds usually are: pricing, productivity and one very strong segment carrying the rest. The question for the fourth quarter is whether Safety & Industrial can keep growing at 9% while the softer segments stabilize — and whether the Amazon relationship converts from a warrant headline into purchase orders. For now, though, 3M has done the thing it kept failing to do for years: it surprised Wall Street in the right direction, twice in a row by the market’s count, and got paid for it. See more from Previously’s Business Desk coverage and Tuesday’s other earnings story, GM’s beat that the market sold anyway — a useful reminder that the same numbers can read very differently depending on the story attached to them.
Sources · 4 sources
- Zacks — Compared to Estimates, 3M (MMM) Q3 Earnings: A Look at Key Metrics (October 20, 2026)
- Seeking Alpha — 3M Non-GAAP EPS of $2.50 Beats by $0.12, Revenue of $6.6B Misses by $10M (October 20, 2026)
- Tickeron — 3M (MMM) Third-Quarter 2026 Earnings Recap (October 20, 2026)
- TradingView News / StockStory — Why Is 3M (MMM) Stock Rocketing Higher Today (October 20, 2026)