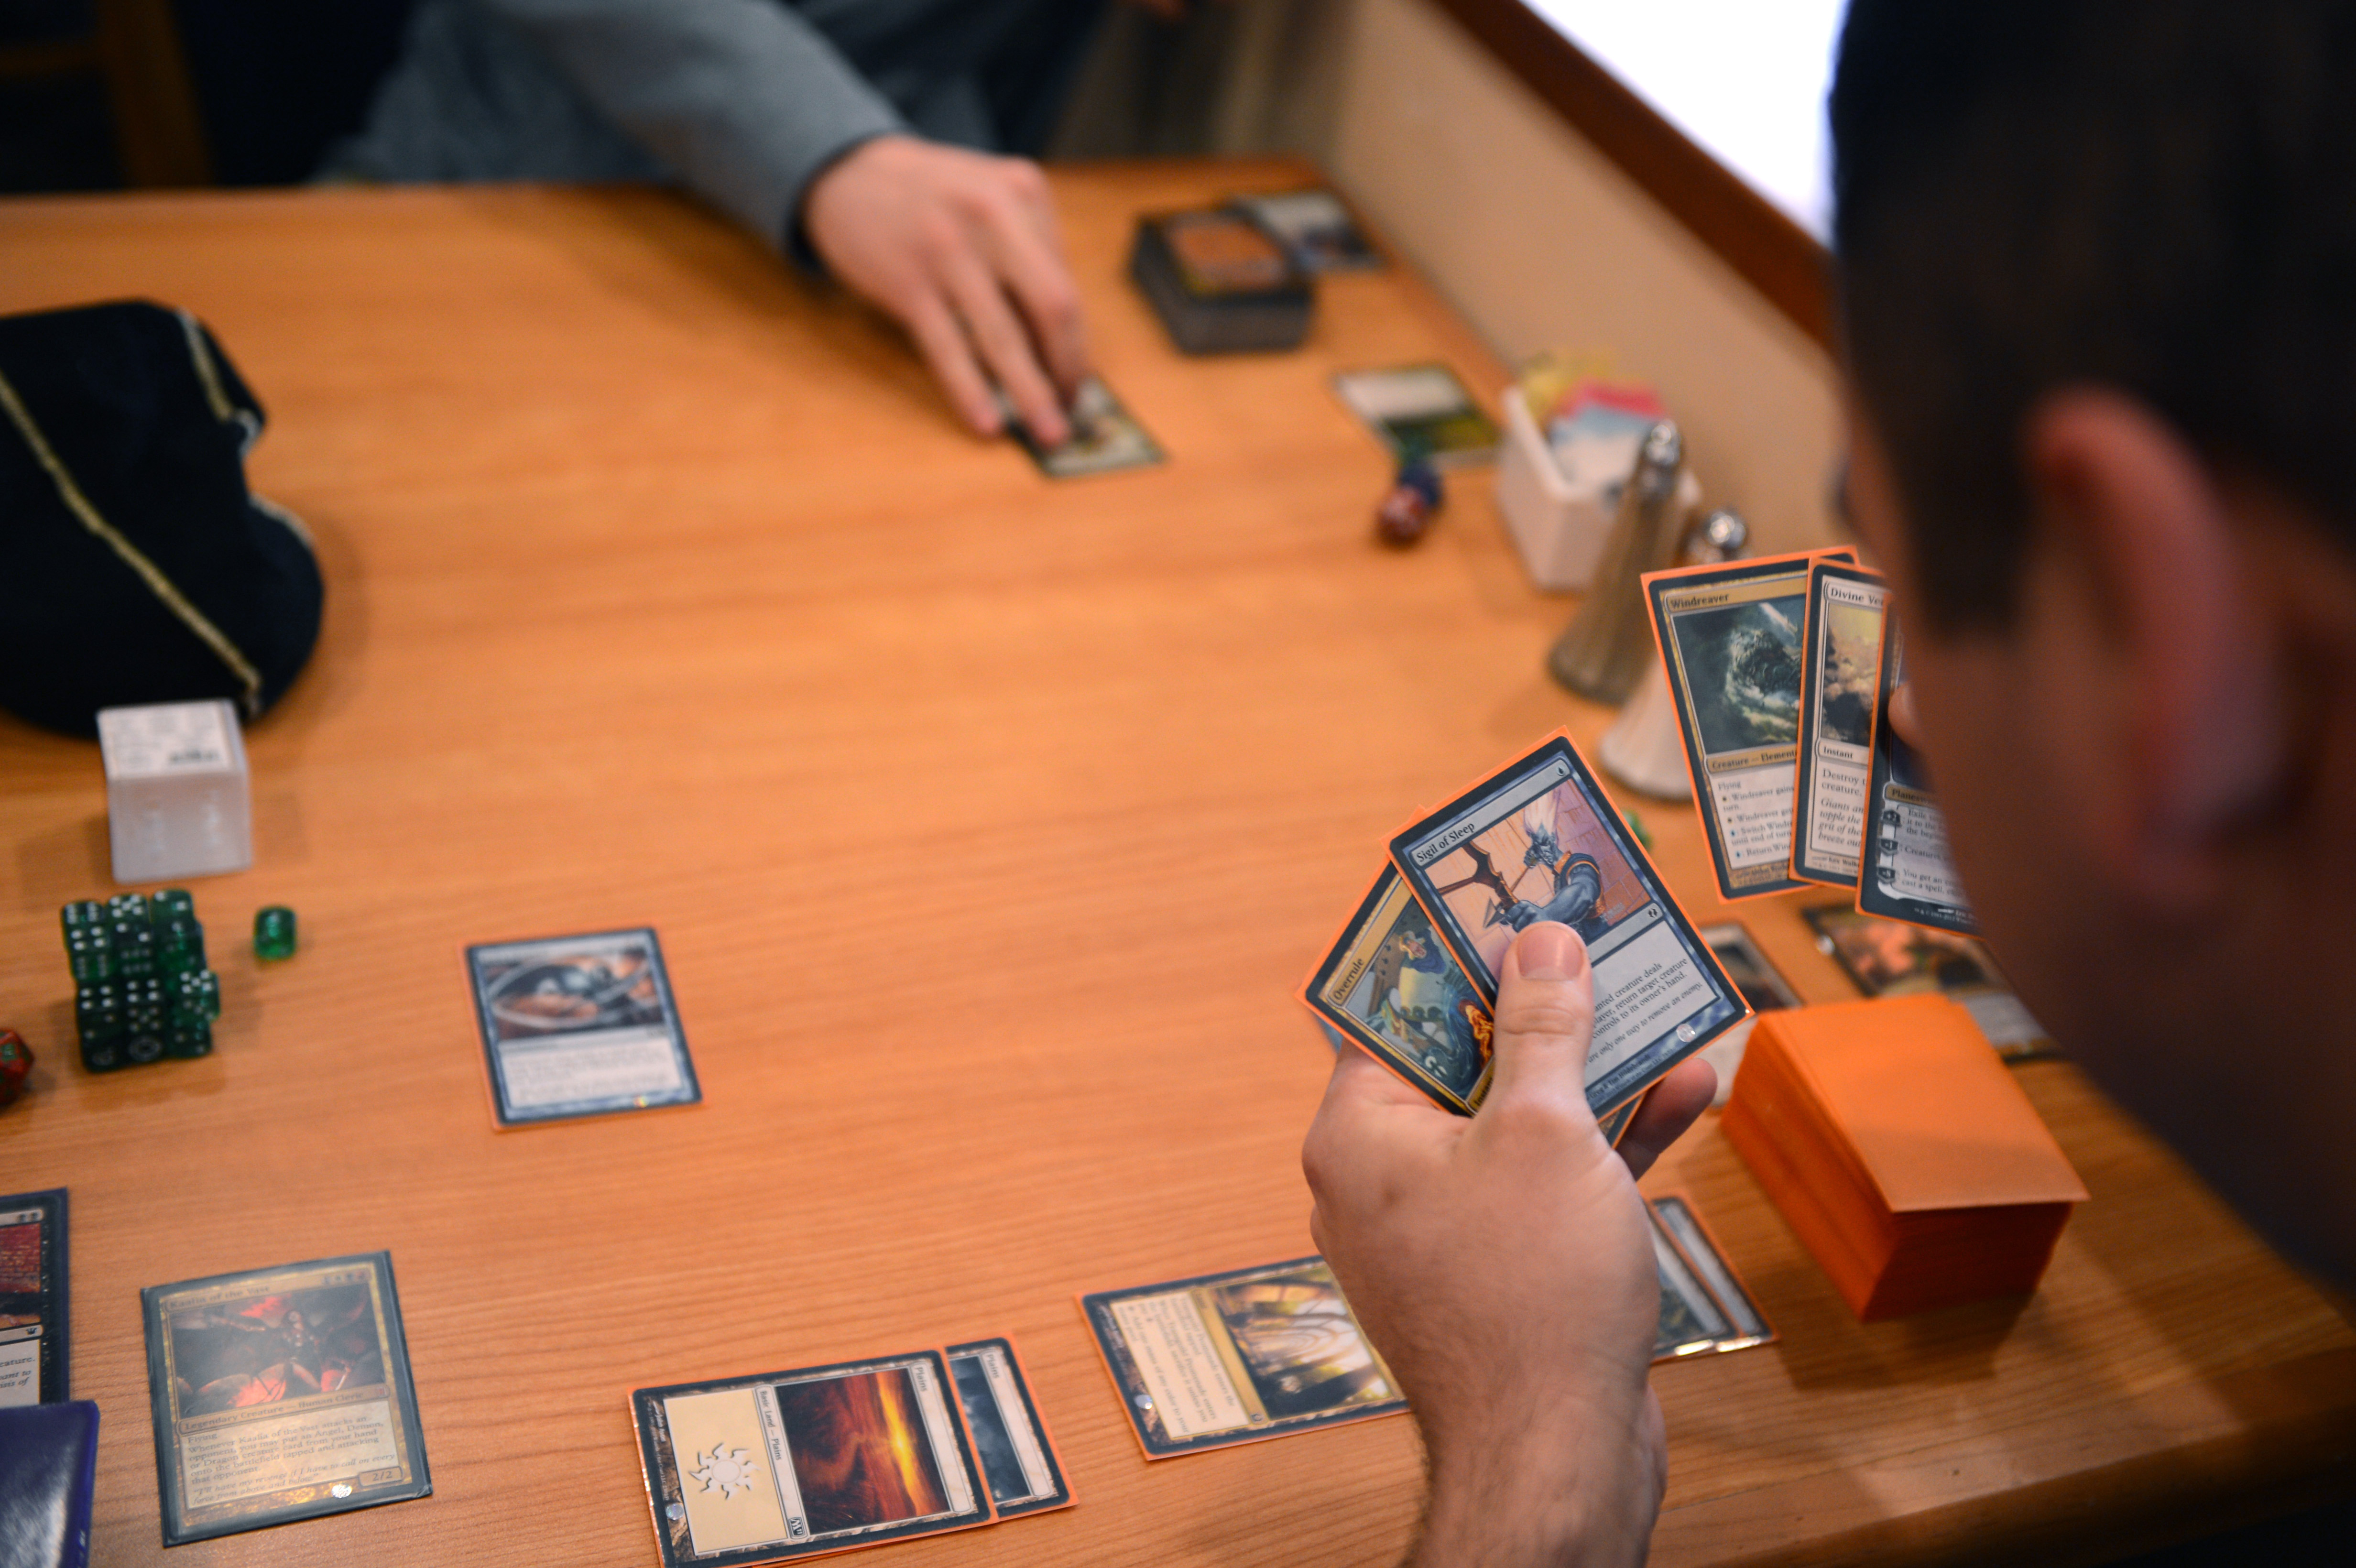

The most profitable piece of cardboard in American business did it again. Hasbro’s third quarter, reported Tuesday, October 20, 2026, was powered by a trading card game old enough to have mortgages: Magic: The Gathering revenue jumped 34% to $616.1 million, crossing $600 million in a single quarter for the first time, according to Barron’s. Companywide revenue grew 15% to $1.60 billion, comfortably ahead of Wall Street’s $1.48 billion estimate, and adjusted earnings of $2.90 a share crushed the $1.86 consensus, Barron’s reported. Hasbro raised its full-year outlook, doubled its buyback target, and watched its stock climb 6.2% to $104.57 — among the best performances in the S&P 500 on the day.
Wizards is the company now
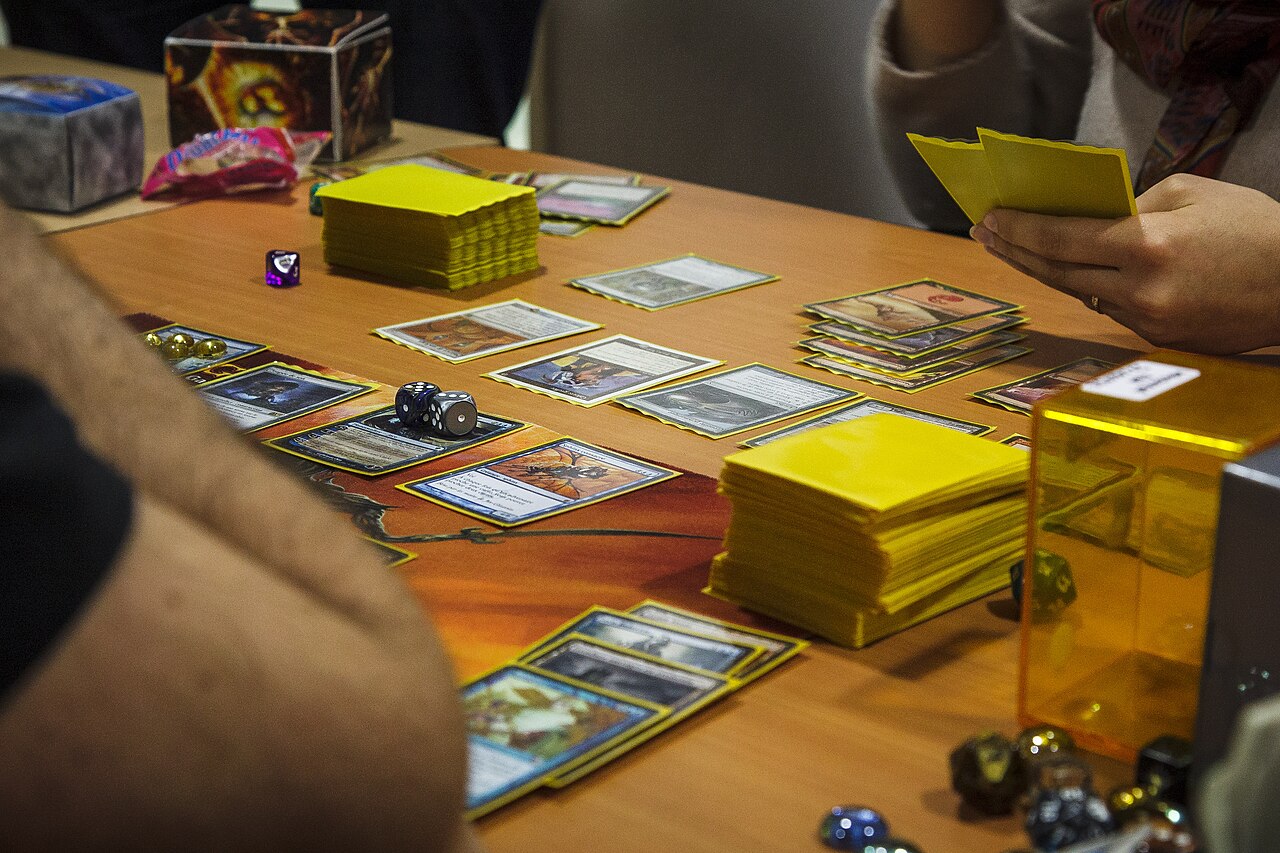
The segment math tells the story plainly. Wizards of the Coast and Digital Gaming revenue rose 31% to $747.2 million, according to the company’s results as reported by The Toy Book, with Magic supplying $616.1 million of that total. Monopoly Go! contributed another $41 million to the segment. Put differently, the division built around a fantasy card game and licensed digital play now delivers nearly half of Hasbro’s revenue — and, at segment margins near 49%, the overwhelming share of its profit. The toymaker that sells Play-Doh and Nerf is, economically, a games company with a toy business attached.
“With a Magic lineup that keeps building, we expect a strong finish to 2026 and continued growth in 2027,” CEO Chris Cocks said in the company’s release, according to Barron’s. The quarter’s Magic growth was fueled by releases including The Hobbit and Reality Fracture sets, according to The Toy Book, continuing a run in which licensed crossovers — Marvel and Final Fantasy among the recent headliners — have pulled new collectors into the game while longtime players keep buying. Grafa reported that Cocks called it Hasbro’s fourth consecutive quarter of double-digit revenue growth, crediting strong demand for Magic and licensing partnerships.
The toy aisle held up its end
Consumer products, the traditional business, grew 4% to $827.9 million, led by Marvel, K-Pop Demon Hunters and Transformers, according to The Toy Book, with Beyblade and the release of Blooms by Play-Doh also contributing. Entertainment revenue rose 9%, with adjusted operating profit up 63% on a more favorable licensing mix. Adjusted operating profit for the whole company rose 52% to $541 million, including roughly $55 million of tariff refunds, according to Grafa — a reminder that even a quarter this strong carried a one-time tailwind investors will strip out of their models. Reported operating profit was $517 million, and diluted earnings came in at $2.77 a share.
Barron’s put the collectibles boom in wider context: GameStop’s collectibles and trading card sales surged 57% to $356.3 million in its fiscal second quarter, representing about 45% of its total sales, and Mattel stock rose 0.9% on Tuesday in Hasbro’s wake. Adults buying cards — for play, for collecting, and, let’s be honest, sometimes for the speculation — have become one of the most dependable consumer stories in retail. Hasbro sits at the center of it with the category’s defining franchise.
It is worth treating the digital side as more than a footnote, because Hasbro increasingly does. Monopoly Go! has now contributed $127 million year to date, according to The Toy Book, and the Wizards segment pairs that mobile income with tabletop and digital Magic play that keeps players inside the franchise between set releases. That mix — cardboard, screens and licensing feeding the same brands — is the strategy Cocks has been building toward, and the third quarter is its clearest proof yet: growth did not come from a single hit toy, but from an ecosystem that monetizes the same fans three different ways.
A raise, a bigger buyback, and a test ahead
Management converted the quarter into a higher bar for the year. Hasbro now expects full-year revenue growth of 7% to 9% in constant currency, up from 5% to 7% previously, and adjusted EBITDA of $1.58 billion to $1.63 billion, up from $1.45 billion to $1.5 billion, according to Barron’s. The company doubled its annual share repurchase target to $400 million, and returned $206 million to shareholders through dividends and buybacks during the quarter while putting $79 million toward debt reduction, according to Grafa.
The honest question hanging over the stock is durability. Magic’s growth has been supercharged by premium and licensed sets that ask collectors to open their wallets again and again; the formula has now worked for four straight double-digit quarters, but every crossover raises the bar for the next one. Barron’s noted the shares were on track for their highest close since February 11 and had already gained 20% this year through Monday — expectations are no longer low. What Tuesday proved is that, for now, the demand is real, the numbers are large, and a game printed on cardboard in 1993 is carrying a century-old toy company to its best year in memory. Not bad for a deck of cards.
Sources · 3 sources
- Barron’s — Hasbro’s Earnings Show It’s Winning Big With Trading Cards (October 20, 2026)
- The Toy Book — Hasbro Raises 2026 Outlook Again as Magic Breaks $600 Million in Q3 (October 20, 2026)
- Grafa — Hasbro Q3 2026 Revenue Rises 15% to $1.6 Billion (October 20, 2026)