
NEW YORK THURSDAY, OCTOBER 15, 2026
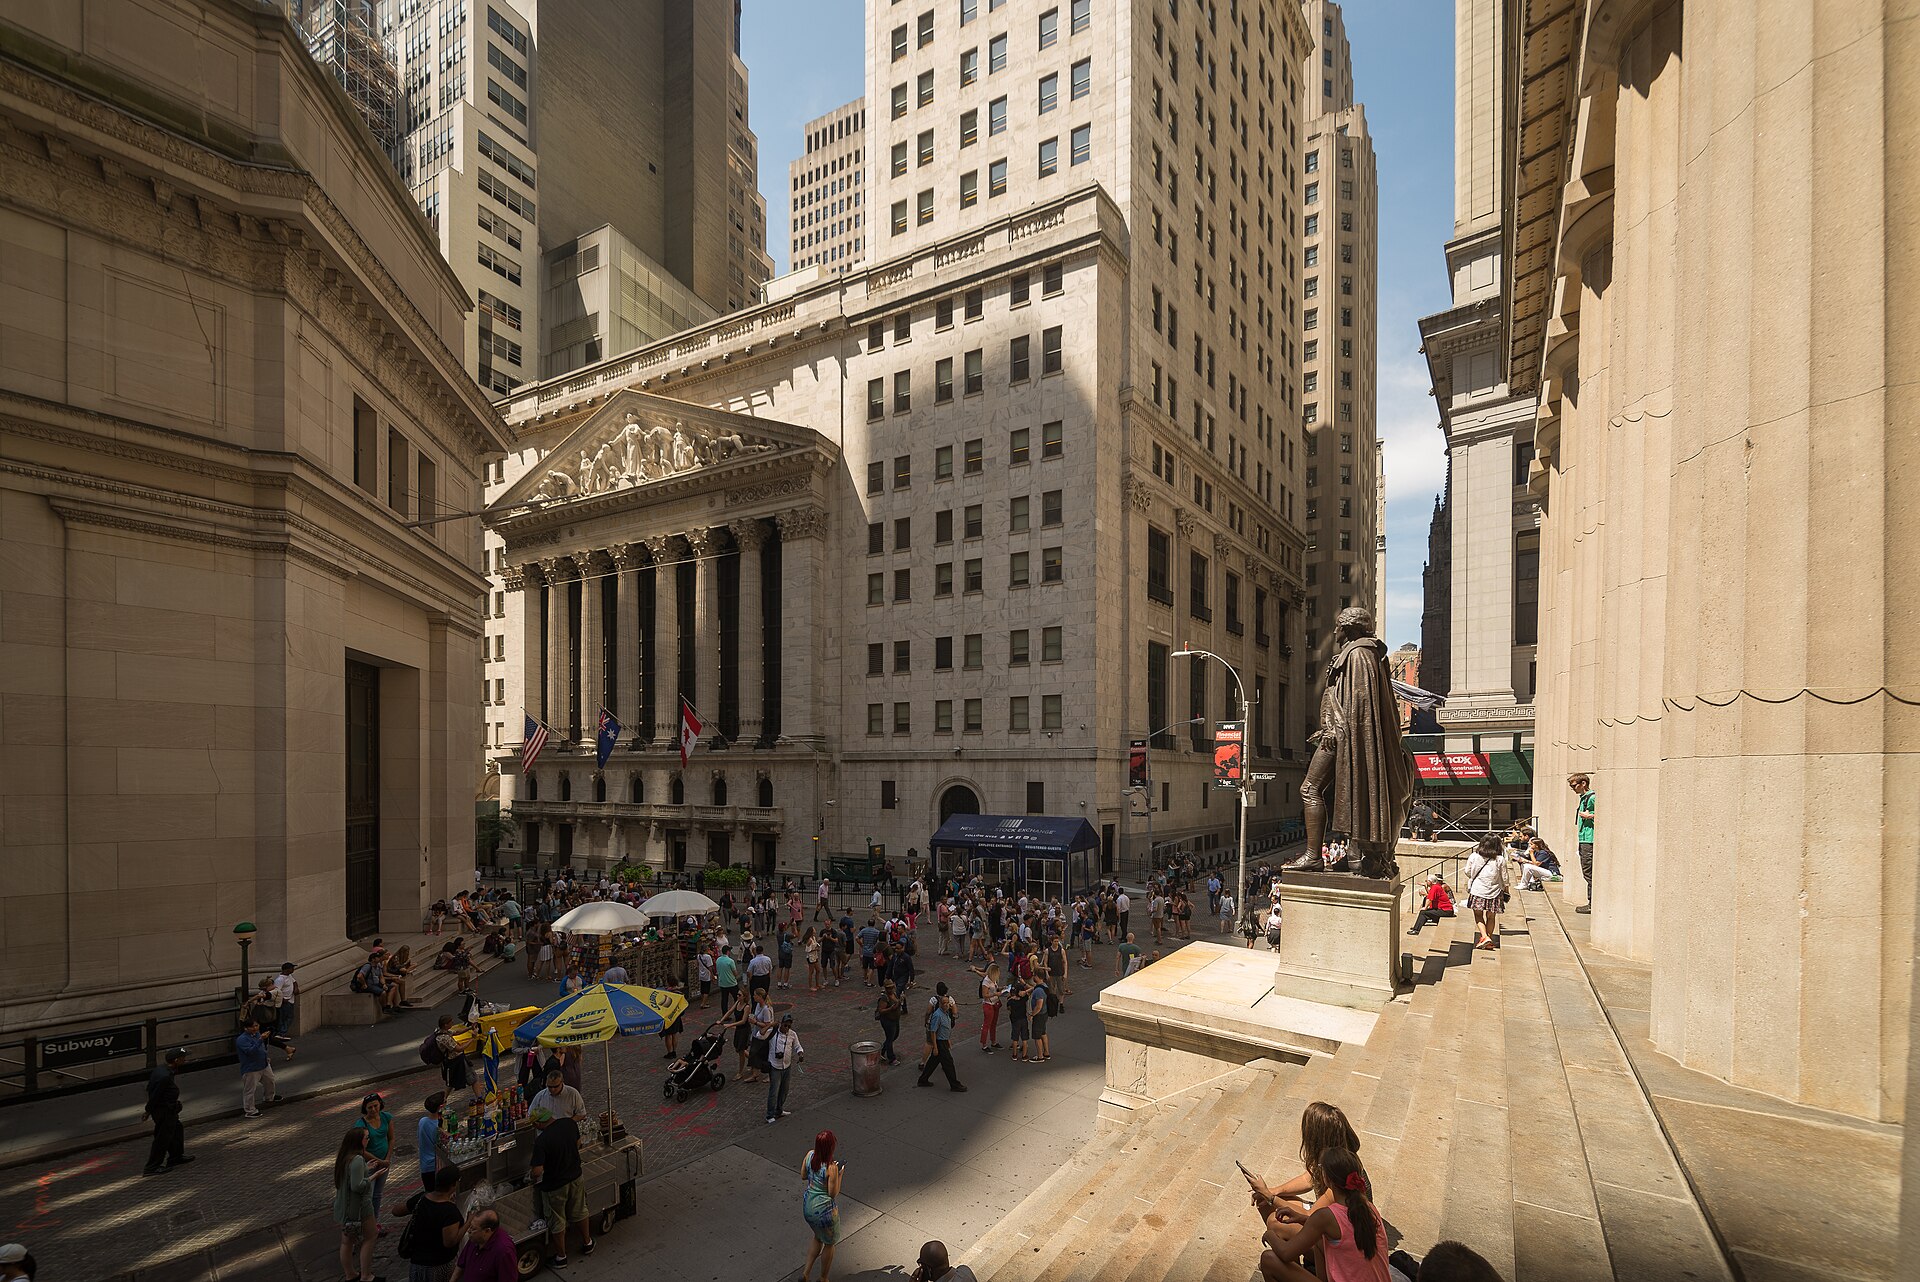
Wall Street woke up Thursday to an uncomfortable split screen. On one side, the biggest chipmaker on earth had just reported the strongest quarter in its history, the sixth record in a row, powered by relentless demand for artificial intelligence hardware. On the other side, a hotter-than-expected inflation report from the day before was still pulling the floor out from under technology stocks, and futures pointed to a second straight session of selling before a fresh wave of economic data even landed.
The tension between those two stories — booming real demand for AI chips and a macro environment that punishes the valuations built on that demand — is now the defining argument in this market. Wednesday's session showed which side is winning in the short term. The S&P 500 closed at 7,718.94, down 1.11 percent. The tech-heavy Nasdaq Composite fell harder, dropping 1.88 percent to 26,692.87, while the Dow Jones Industrial Average, with far less exposure to the AI trade, slipped just 0.09 percent to 51,621.48. That spread tells the story in one line: this was not a broad panic, it was a targeted repricing of the technology complex.
The inflation report that changed the week
The trigger was the September Consumer Price Index. Headline inflation rose 0.6 percent in the month and 3.7 percent from a year earlier, above the 3.6 percent annual pace economists had expected and an acceleration from August's 3.4 percent. Core inflation, which strips out food and energy, rose 0.3 percent on the month and 2.6 percent on the year. Investopedia noted the single biggest driver was gasoline, which jumped 9.1 percent in September alone — a reminder that energy prices, heavily influenced by the ongoing conflict in the Middle East, are feeding directly back into the cost of living.
For investors, the damage is not the number itself so much as what it does to the Federal Reserve. A reacceleration in headline inflation, arriving weeks before the Federal Open Market Committee meets on October 27 and 28, strengthens the hand of officials who want to keep policy tight — or tighten further — and weakens the case for any near-term relief. Rate-sensitive growth stocks, whose valuations rest on profits expected years from now, are the first casualties when that math shifts, and they were again on Thursday morning.

Chip stocks take the brunt of the selling
Nowhere was the repricing more violent than in the names that had carried the AI rally. CoreWeave, the cloud infrastructure provider whose stock had become a pure-play bet on AI data center demand, plunged 15.5 percent on Wednesday. Dell Technologies fell 11.3 percent, Oracle dropped 8.8 percent, and Marvell Technology lost 8.7 percent. Nvidia, the industry's bellwether, fell a comparatively modest 3.2 percent — though for a company of its size, even that move erased an enormous amount of market value in a single session.
The Philadelphia Semiconductor Index fell 4.3 percent, its sixth consecutive loss. A six-day slide in the chip index is significant because it suggests the selling has moved past a one-day reaction to a single data print. Fund managers appear to be trimming exposure across the whole AI supply chain — designers, server makers, cloud builders — rather than picking off individual disappointments. When the trade that has powered the market for two years starts to unwind in unison, index-level support gets thin quickly.
Bank earnings split the difference
Earnings season offered no refuge. Bank of America fell 4.8 percent after reporting earnings per share of $0.91 — a figure weighed down by a $1.2 billion regulatory charge. Adjusted for that charge, earnings were $1.08 per share, but revenue of $30.1 billion missed expectations, and investors chose to focus on the miss and the charge rather than the underlying number. A regulatory hit of that size also invites questions about what else might be coming for the big banks as supervisors work through their review agendas.
Morgan Stanley told the opposite story on performance and still could not escape the tape. The bank beat expectations with earnings of $3.03 per share against estimates of roughly $2.91, and its equities trading desk had a standout quarter, with revenue up 41 percent to $5.8 billion — evidence that volatile markets are good business for firms positioned to trade them. Even so, the stock slipped about 2.8 percent on the day, a sign of how heavy the broader mood was: on Wednesday, even a clean beat was treated as an opportunity to sell.

TSMC's record quarter was not enough
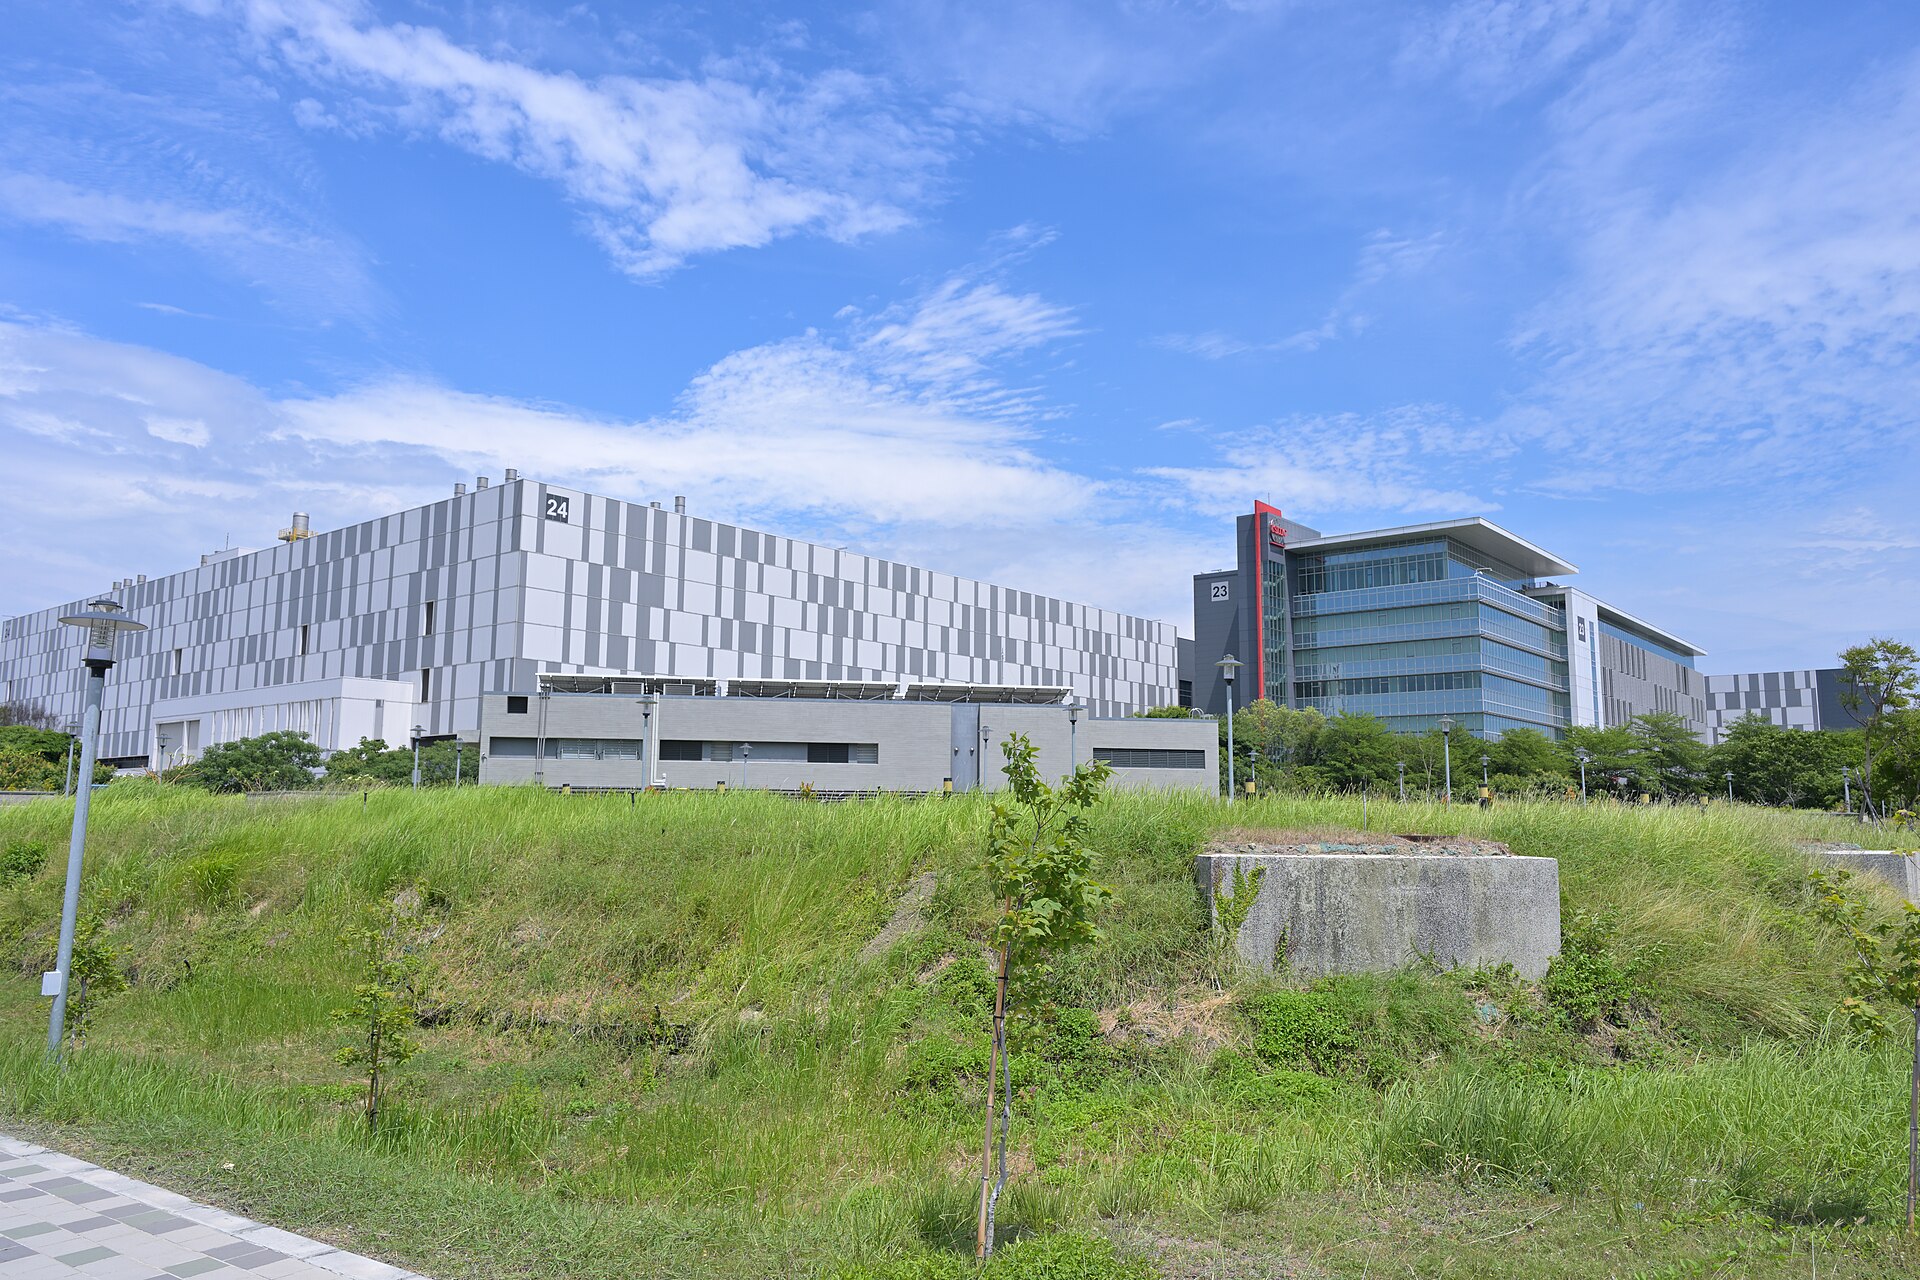
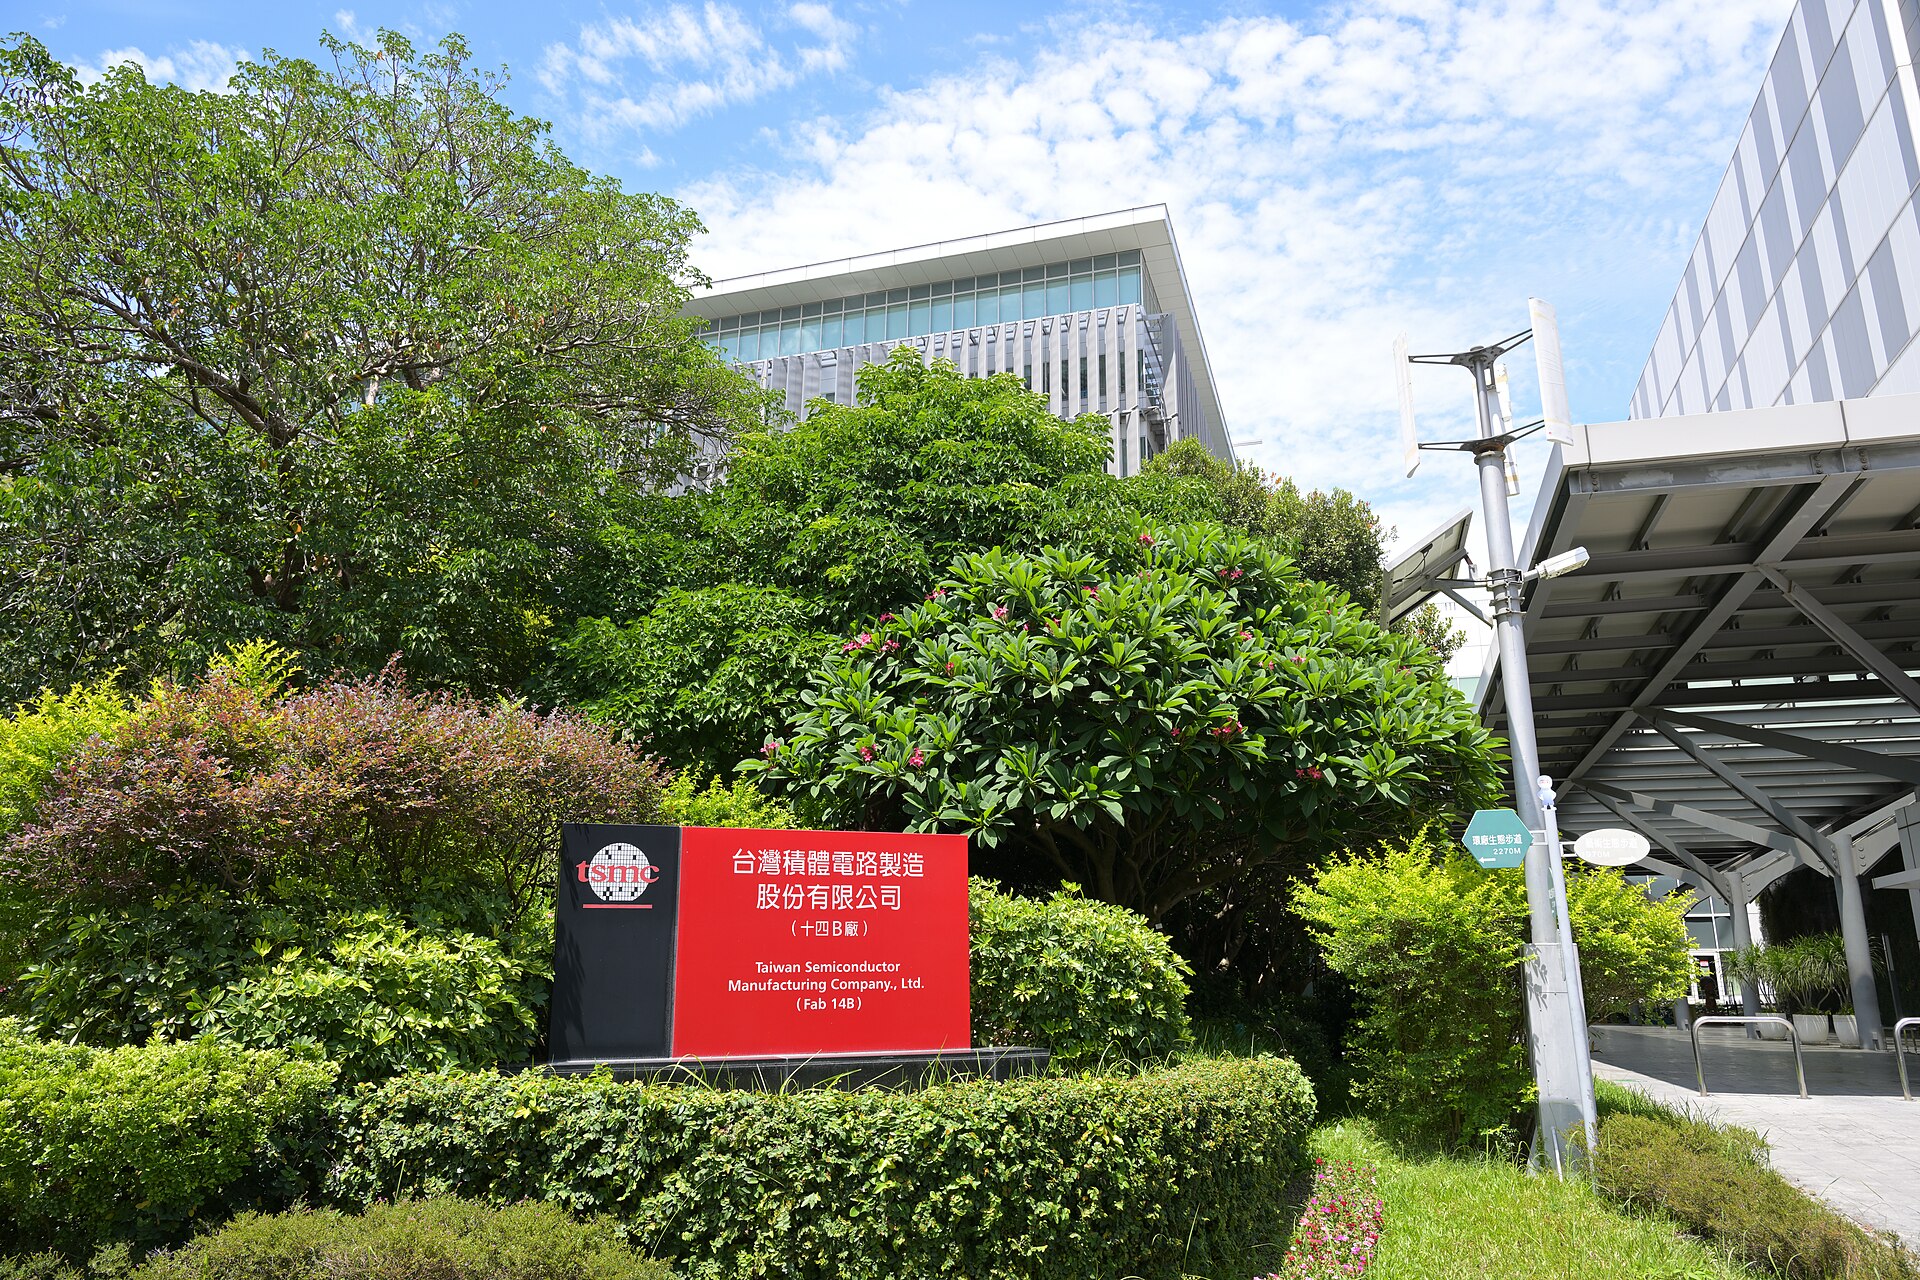
Against that backdrop, Taiwan Semiconductor Manufacturing Company delivered numbers that would headline any normal week. Third-quarter revenue reached NT$1.494 trillion, roughly $46.7 billion, up 50.9 percent from a year earlier. Net profit climbed 68.7 percent to NT$763.1 billion, with earnings of NT$29.43 per share — the company's sixth consecutive record quarter. The mix explains why: 2-nanometer production already accounts for 8 percent of wafer revenue, and advanced nodes together represent 79 percent of the total, reflecting how completely the world's AI buildout now runs through TSMC's most sophisticated lines.
TradingKey's analysis of the results noted that management's guidance pointed higher still, with fourth-quarter revenue expected between $52.3 billion and $54.3 billion. In other words, the fundamental story underneath the AI trade — real orders, real capacity, real pricing power at the foundry level — remains intact and accelerating. Yet TSMC's U.S.-listed shares were lower in premarket trading Thursday, according to Investopedia's morning briefing. That disconnect is the market's current mood in miniature: the question investors are asking is no longer whether AI demand is real, but how much they should pay for it while inflation is rising and the Fed is cornered.
What Thursday brings
The day ahead offers little chance to catch a breath. At 8:30 a.m. Eastern, investors get three releases at once: the Producer Price Index, which will show whether pipeline price pressures echo the consumer data; September retail sales, the clearest read on whether higher gasoline prices are finally biting household spending; and weekly jobless claims, the timeliest gauge of whether the labor market is cracking under tight policy. Any combination of hot wholesale prices and weak consumption would hand the market the worst of both worlds.
Premarket signals were mixed but pointed the same direction for tech. XTB's morning market coverage put Nasdaq futures down 1.2 percent early Thursday, S&P 500 futures off 0.3 percent, and Dow futures up 0.2 percent — the same defensive rotation visible in Wednesday's close. The 10-year Treasury yield sat near 5.09 percent, gold rose 1.4 percent to about $4,165 an ounce as investors paid up for shelter, and bitcoin traded around $80,800, well off its recent highs above $84,000. WTI crude held near $95.40 a barrel, keeping the energy-inflation loop very much alive.
For broader context on how the same inflation shock is rippling through overseas markets, see our coverage of the selloff in Asian stocks, where the Kospi and Nikkei have been hit by the same unwind in AI trades. And with European leaders meeting in Brussels this week, the policy debate over growth, budgets and trade is running in parallel — read our summit coverage for the other half of the global picture.
The Fed meeting now looms over everything
All of it funnels toward October 27 and 28, when the FOMC next decides on rates. A week ago, the debate was about the timing of cuts. After the September CPI, the debate is about whether the Fed can afford to stand still. Thursday's PPI print will either soften that conversation or harden it, and retail sales will tell policymakers whether the consumer is absorbing higher prices or starting to fold. Until then, the market's verdict from Wednesday stands: the AI trade is wounded, the banks cannot carry the tape alone, and even a record quarter from the most important chipmaker in the world is not, by itself, enough to turn the mood.
More from Previously
- Asia stocks sell off as the AI trade unwinds in Seoul and Tokyo
- EU leaders gather in Brussels over China exports and the bloc budget
- Pope Leo faces lung cancer surgery, Vatican confirms
Sources · 4 sources
- Investopedia — 5 Things to Know Before the Stock Market Opens, Oct. 15, 2026
- Investopedia — How Much Traders Expect TSMC Stock to Move After Earnings
- TradingKey — TSMC third-quarter analysis
- XTB — morning market coverage, Oct. 15, 2026 (via KuCoin/XTB)