
NEW YORK THURSDAY, OCTOBER 15, 2026
The two biggest bank stories of earnings season landed on the same morning, and they pointed in opposite directions. Bank of America reported earnings weighed down by a $1.2 billion regulatory charge and a revenue line that missed what Wall Street was looking for, and its stock fell 4.8 percent. Morgan Stanley, by contrast, beat expectations outright, powered by an equities trading desk that grew revenue 41 percent — and its stock still slipped about 2.8 percent. When a clean beat cannot hold its gains, the market is telling you the problem is bigger than any one bank.
That bigger problem is inflation, and Thursday morning puts it to a three-part test. At 8:30 a.m. Eastern, investors get the Producer Price Index, September retail sales and weekly jobless claims in a single blast — the first full read on prices, consumers and jobs since Wednesday's hotter-than-expected Consumer Price Index reset expectations for the Federal Reserve's October 27–28 meeting. Bank earnings set the tone; Thursday's data will decide whether the tone hardens into a trend.
Bank of America: a charge, a miss, and a 4.8 percent fall
Bank of America's quarter, as summarized in Investopedia's earnings coverage, came in two layers. The reported number was earnings of $0.91 per share, a figure that included a $1.2 billion regulatory charge. Strip that charge out and the bank earned an adjusted $1.08 per share — a respectable result that investors largely ignored. What they focused on instead was revenue of $30.1 billion, which missed expectations, and the charge itself, which at that size inevitably raises the question of whether more regulatory costs are coming for the largest U.S. banks.
The stock's 4.8 percent drop — one of the sharpest among big-bank shares on Wednesday — reflects that ordering of concerns. A one-time charge can be forgiven; a revenue miss in a quarter when trading and deal-making conditions were favorable is harder to explain away, because it suggests the shortfall is about the bank's own execution rather than the environment. Coming at the start of earnings season, the result also sets a demanding bar for the banks still to report: if revenue is light at a bank of America's scale, investors will assume the same pressure exists elsewhere until proven otherwise.
Morgan Stanley beat — and the market sold it anyway
Morgan Stanley's report was the mirror image. Earnings came in at $3.03 per share against estimates of roughly $2.91, according to the figures compiled in Investopedia's morning briefing, and the standout was equities trading, where revenue jumped 41 percent to $5.8 billion. That is what a trading franchise is supposed to do in volatile markets: when clients are repositioning at speed — exactly what an inflation shock forces them to do — the desks that intermediate that flow earn exceptional fees.
And yet the stock slipped about 2.8 percent on the day. Traders who follow bank stocks call this pattern "selling the news": the results were strong, but the macro backdrop was stronger. With the S&P 500 closing down 1.11 percent at 7,718.94, the Nasdaq down 1.88 percent at 26,692.87 and the Dow nearly flat, down 0.09 percent at 51,621.48, Wednesday's tape punished almost everything with a growth or rate-sensitive label. Morgan Stanley's beat was real; it simply was not the story the market was trading.
The inflation backdrop banks cannot escape
The reason sits in Wednesday's CPI report. September inflation rose 0.6 percent on the month and 3.7 percent from a year earlier, above the 3.6 percent expected and faster than August's 3.4 percent pace, with core inflation up 0.3 percent on the month and 2.6 percent on the year. Investopedia noted the single biggest driver was gasoline, up 9.1 percent in the month — energy costs, swollen by the war in the Middle East, passing directly into household budgets and, from there, into the Fed's reaction function.
For banks, hot inflation cuts both ways, which is why the sector's reaction was so uneven. Higher-for-longer interest rates support lending margins, but they also raise deposit costs, pressure borrowers, and — as Bank of America's charge reminded investors — arrive alongside an active regulatory agenda. Meanwhile the day's worst damage sat in the technology complex that banks increasingly serve and finance: the Philadelphia Semiconductor Index fell 4.3 percent for a sixth straight loss, with CoreWeave down 15.5 percent, Dell down 11.3 percent, Oracle down 8.8 percent, Marvell down 8.7 percent and Nvidia down 3.2 percent.
Thursday's 8:30 a.m. gauntlet
That is the setup for Thursday's data. The Producer Price Index will show whether wholesale price pressures match the consumer report; if pipeline inflation is also accelerating, the case for the Fed to stay restrictive through its October 27–28 meeting — or go further — gets materially stronger. Retail sales will show whether households are absorbing higher gasoline prices or starting to cut back, the distinction between an inflation problem and a stagflation problem. Weekly jobless claims, the timeliest labor gauge, will show whether tight policy is finally cracking employment, which would complicate the Fed's calculus in the opposite direction.
Premarket positioning, in XTB's morning market coverage, showed investors braced but not panicked: Nasdaq futures were down 1.2 percent, S&P 500 futures off 0.3 percent, and Dow futures up 0.2 percent — the same defensive rotation, away from tech and toward value, that defined Wednesday's close. The 10-year Treasury yield sat near 5.09 percent, gold rose 1.4 percent to about $4,165 an ounce, bitcoin traded around $80,800, and WTI crude held near $95.40 a barrel, keeping the energy-to-inflation loop firmly in place heading into the releases.
TSMC's record quarter, in a supporting role
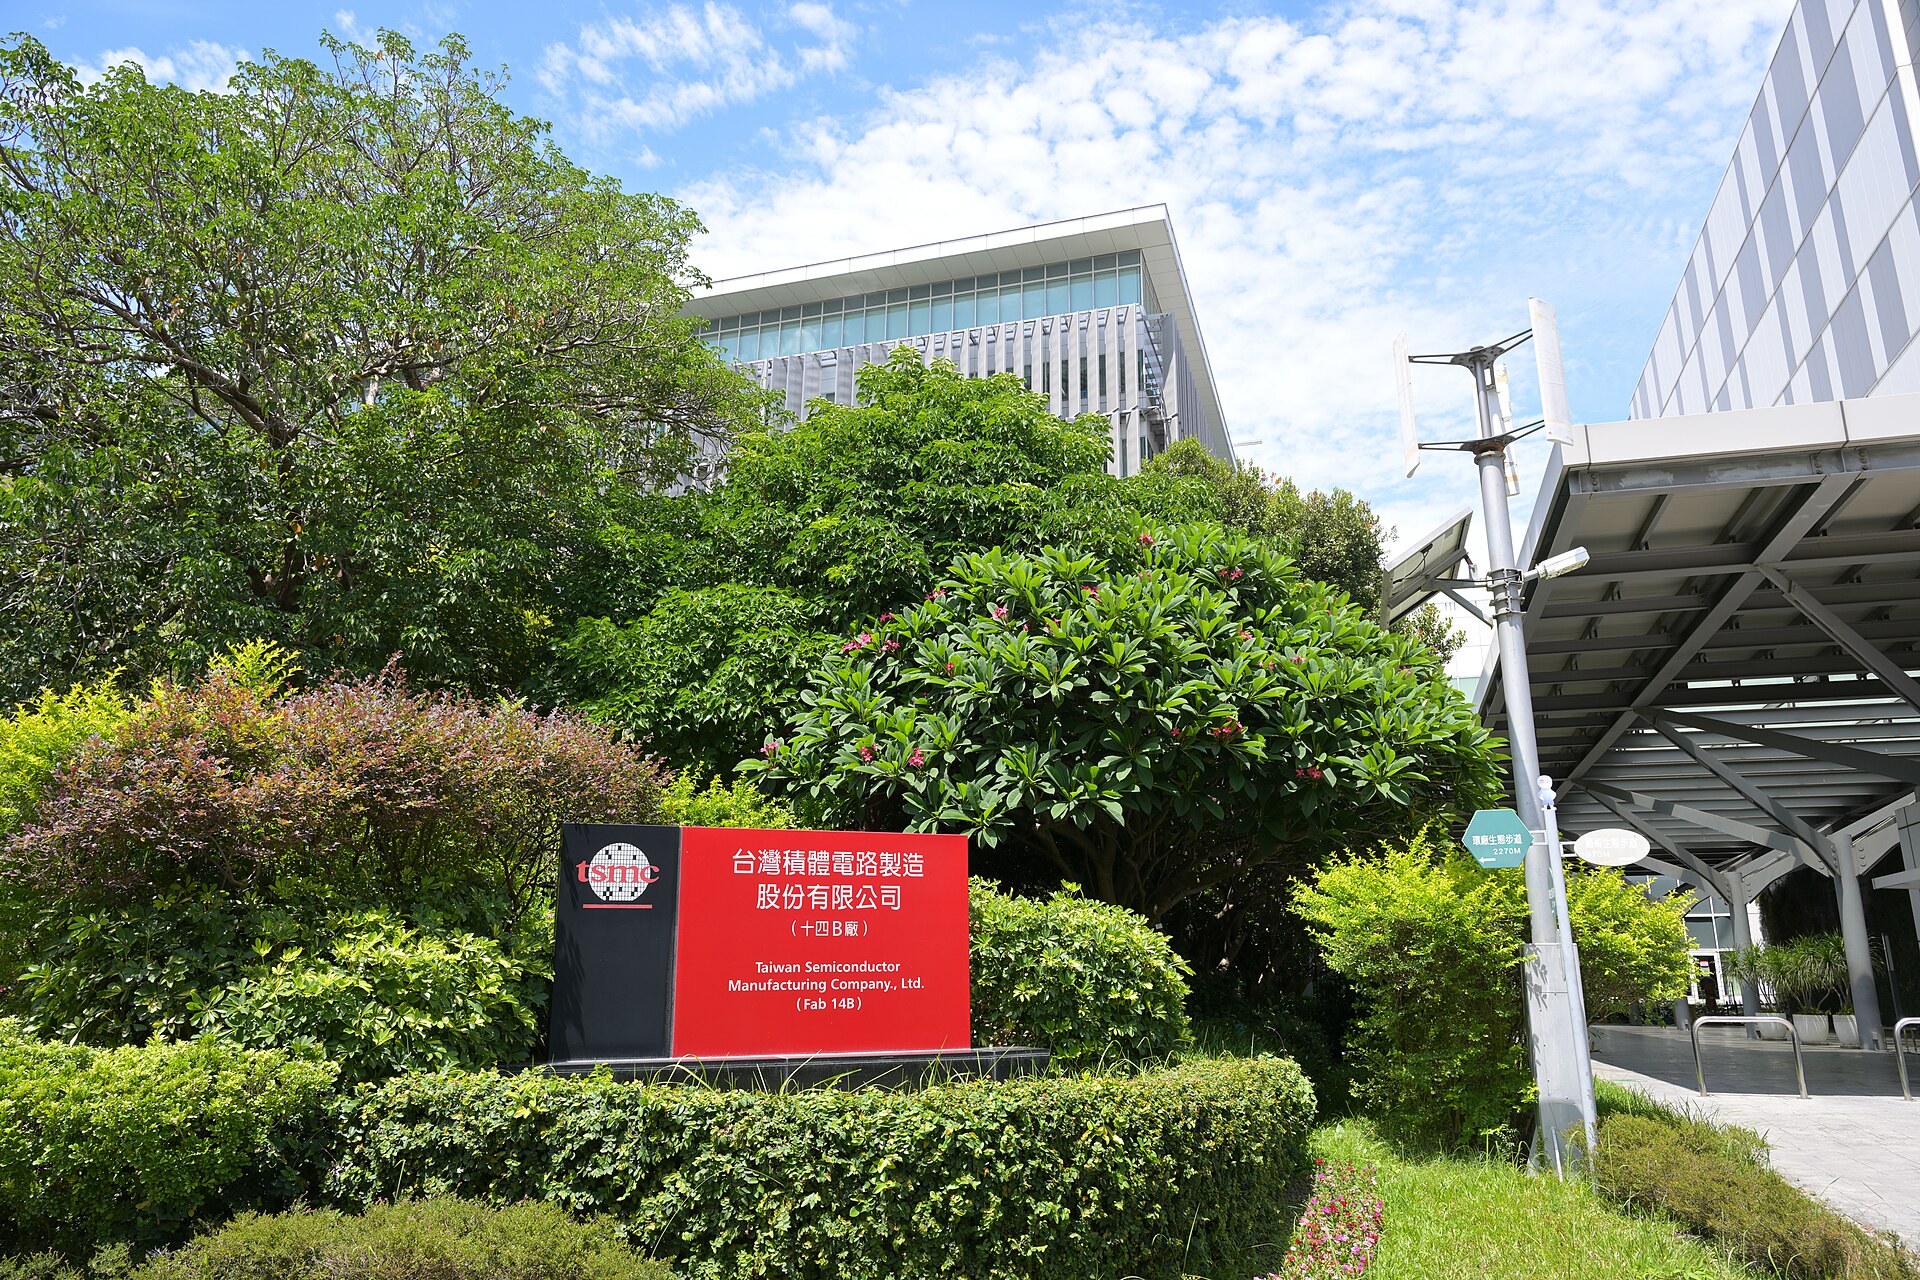
The week's other major earnings story would headline any normal cycle. TSMC, the world's largest contract chipmaker, reported third-quarter revenue of NT$1.494 trillion — about $46.7 billion, up 50.9 percent from a year earlier — with net profit up 68.7 percent to NT$763.1 billion and earnings of NT$29.43 per share, its sixth consecutive record quarter, according to TradingKey's analysis of the results. Advanced nodes made up 79 percent of wafer revenue, with the newest 2-nanometer process already at 8 percent, and TradingKey noted management guided fourth-quarter revenue to between $52.3 billion and $54.3 billion. Even so, TSMC's U.S.-listed shares were lower in premarket trading Thursday, per Investopedia — one more sign that this week belongs to the macro data, not to individual company performance, however strong.
What to watch
By 8:31 a.m. Eastern, the market will know whether Wednesday was a one-day repricing or the start of something larger. A soft PPI paired with resilient retail sales would let bank stocks recover on their fundamentals — Morgan Stanley's trading strength and even Bank of America's adjusted earnings would look different against a calmer backdrop. A hot PPI paired with weak sales would do the opposite, and would send investors into the October 27–28 FOMC meeting pricing a central bank with no good options. The banks have reported; now the data decides.
For the regional side of this week's market shock, see our coverage of the selloff in Asian stocks, and for the policy debate running in parallel overseas, our report on the EU leaders' summit in Brussels.
More from Previously
- Asia stocks sell off as the AI trade unwinds in Seoul and Tokyo
- EU leaders gather in Brussels over China exports and the bloc budget
- Pope Leo faces lung cancer surgery, Vatican confirms
Sources · 4 sources
- Investopedia — 5 Things to Know Before the Stock Market Opens, Oct. 15, 2026
- Investopedia — How Much Traders Expect TSMC Stock to Move After Earnings
- TradingKey — TSMC third-quarter analysis
- XTB — Morning market coverage, Oct. 15, 2026 (via KuCoin/XTB)